For millions of Americans burdened by student loan debt, the prospect of relief is a constant hope. As we look ahead to 2026, new federal student loan forgiveness programs are emerging, offering a beacon of light for borrowers. These initiatives, building upon existing frameworks and introducing new provisions, hold the potential to significantly reduce outstanding balances, with some individuals possibly seeing up to 10% of their debt erased. Understanding these evolving programs is crucial for anyone seeking financial liberation from student loans. This comprehensive guide will delve into the intricacies of what’s on the horizon for student loan forgiveness 2026, helping you navigate the landscape and prepare to seize these opportunities.
The landscape of student loan debt in the United States is vast and complex, affecting millions of individuals and impacting the broader economy. With over $1.7 trillion in outstanding student loan debt, the financial strain on borrowers is undeniable. This debt can delay major life milestones such as homeownership, marriage, and starting a family. Recognizing this pervasive issue, the federal government has continuously explored and implemented various strategies to alleviate the burden. The upcoming changes and potential new programs in 2026 represent a significant step in these ongoing efforts, aiming to provide targeted relief and a clearer path to financial stability for many.
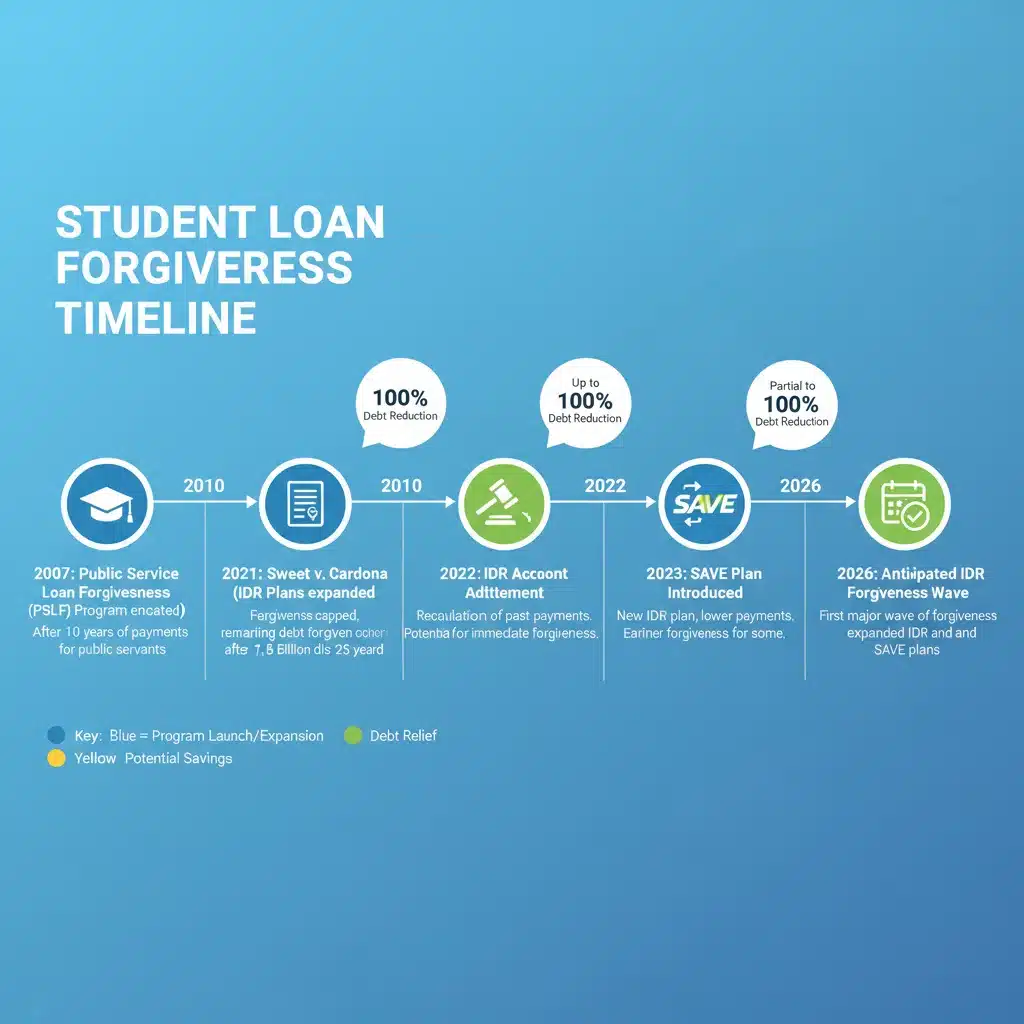
Historically, federal student loan forgiveness has been available through specific programs like Public Service Loan Forgiveness (PSLF), Income-Driven Repayment (IDR) plans, and borrower defense to repayment. However, these programs often came with stringent eligibility requirements, complex application processes, and sometimes, a lack of awareness among borrowers. The new initiatives anticipated for 2026 are designed to address some of these shortcomings, making relief more accessible and impactful for a wider range of borrowers. Our focus here will be on demystifying these programs, ensuring you have the knowledge to assess your eligibility and take the necessary steps to benefit from them.
Understanding the Evolution of Federal Student Loan Forgiveness
The journey of federal student loan forgiveness has been marked by continuous adjustments and expansions. From the initial federal loan programs to the more recent reforms, the goal has largely remained the same: to support students in accessing higher education while also providing mechanisms for debt relief when appropriate. The period leading up to 2026 is no exception, with policymakers and educational institutions working to refine existing programs and introduce new ones that cater to the current economic climate and borrower needs.
Key changes have often stemmed from legislative actions or executive orders designed to address specific challenges. For instance, the COVID-19 pandemic prompted an unprecedented pause on federal student loan payments and interest accrual, highlighting the government’s capacity to implement broad-based relief. While this pause has ended, its impact has undoubtedly informed discussions around future forgiveness initiatives. The lessons learned from previous programs, including their successes and limitations, are being integrated into the design of the 2026 programs, aiming for greater efficiency and equity.
One of the central themes in the evolution of federal student loan forgiveness is the shift towards more targeted relief. While universal forgiveness has been a topic of debate, the trend indicates a preference for programs that address specific borrower circumstances, such as those in public service, those who have been defrauded by institutions, or those experiencing prolonged financial hardship. The anticipated programs for student loan forgiveness 2026 are expected to continue this trend, offering relief that is both meaningful and fiscally responsible.
Key Drivers Behind New Forgiveness Programs
Several factors are driving the introduction and refinement of student loan forgiveness programs. Economic pressures, such as inflation and stagnant wage growth, make it difficult for many graduates to manage their debt alongside other living expenses. The rising cost of higher education itself is another significant contributor, necessitating robust relief options. Furthermore, there is a growing recognition of the societal benefits of reducing student debt, as it can stimulate economic activity and improve overall financial well-being for a substantial portion of the population.
Political considerations also play a role, with both major parties acknowledging the need to address student debt, albeit with different approaches. Advocacy groups and borrower organizations continually push for more comprehensive and accessible relief, keeping the issue at the forefront of policy discussions. These combined forces create an environment where new programs for student loan forgiveness 2026 are not just possible but increasingly probable and necessary.
New Federal Student Loan Forgiveness Programs in 2026: What to Expect
While specific details are still being finalized, and some programs may be subject to legislative approval, several key areas are expected to see significant developments in federal student loan forgiveness by 2026. These include expansions of existing programs, potential new initiatives, and streamlined application processes. The goal is to make relief more accessible and impactful for a broader range of borrowers.
1. Enhanced Income-Driven Repayment (IDR) Plans
Income-Driven Repayment plans have been a cornerstone of federal student loan relief for years, offering lower monthly payments based on a borrower’s income and family size. However, criticisms have often focused on the complexity of enrollment, the long repayment periods before forgiveness, and the potential for a ‘tax bomb’ on forgiven balances. For 2026, we anticipate significant enhancements to IDR plans, making them more generous and easier to navigate.
One of the most anticipated changes is the potential for a more favorable calculation of discretionary income, which would further reduce monthly payments for many borrowers. Additionally, there’s a strong push to shorten the repayment period before forgiveness for certain borrowers, particularly those with smaller initial loan balances. For example, some proposals suggest forgiveness after 10 or 15 years of payments for those who originally borrowed less than $12,000, instead of the standard 20 or 25 years. This could be a game-changer for many, allowing them to achieve student loan forgiveness 2026 much sooner.
Another significant improvement could involve reducing or eliminating the tax liability on forgiven balances under IDR plans. This ‘tax bomb’ has been a major concern for borrowers, as the amount forgiven is currently considered taxable income. Policy discussions are underway to address this, potentially offering a more complete form of relief without the unexpected financial burden at the end of the repayment term. These enhancements aim to make IDR plans a more viable and attractive option for long-term debt management and eventual forgiveness.
2. Expanded Public Service Loan Forgiveness (PSLF)
The Public Service Loan Forgiveness program, designed to forgive the remaining balance on Direct Loans after 120 qualifying monthly payments for those working in public service, has historically been plagued by low approval rates and confusing requirements. While recent temporary waivers have helped many, the focus for 2026 is on making PSLF a more reliable and straightforward path to forgiveness.
Anticipated changes include further clarification of what constitutes ‘qualifying employment’ and ‘qualifying payments,’ reducing the ambiguity that has frustrated many applicants. There’s also a push to simplify the certification process, potentially allowing for automatic tracking of eligible payments for federal employees or those working for verified non-profits. These improvements aim to ensure that dedicated public servants receive the forgiveness they were promised, bolstering the program’s effectiveness and reach.
Furthermore, there may be an expansion of who qualifies for PSLF, potentially including a broader range of non-profit organizations or specific types of public service roles that were previously excluded. This could significantly increase the number of individuals eligible for student loan forgiveness 2026 through this vital program, recognizing the invaluable contributions of public sector workers.
3. Targeted Forgiveness Initiatives
Beyond broad-based programs, 2026 is expected to bring new or expanded targeted forgiveness initiatives designed to address specific borrower populations or circumstances.
- Borrower Defense to Repayment Enhancements: This program allows for the forgiveness of federal student loans if a borrower was defrauded by their school. While significant progress has been made, continuous improvements are expected to streamline the application process, provide clearer definitions of misconduct, and ensure that all eligible borrowers receive timely relief. This is particularly important as more institutions face scrutiny for deceptive practices.
- Total and Permanent Disability (TPD) Discharge: The TPD discharge program offers forgiveness for borrowers who are unable to work due to a total and permanent disability. Efforts are underway to simplify the application process, particularly for those receiving federal disability benefits, and to ensure that more eligible individuals are aware of and can access this crucial relief.
- New Program for Low-Balance Borrowers: There’s increasing discussion around a new, expedited forgiveness pathway for borrowers with very low outstanding balances (e.g., less than $10,000). The administrative cost of servicing these smaller loans can sometimes outweigh the remaining balance, making a quick discharge economically sensible and highly beneficial for borrowers who have struggled for years with a small but persistent debt. This could be a direct pathway to student loan forgiveness 2026 for many.
- Forgiveness for Specific Professions: While PSLF covers many public service roles, there may be new or enhanced programs for specific, high-need professions such as nurses, teachers in underserved areas, or mental health professionals. These programs would aim to address critical shortages in these fields by offering significant debt relief as an incentive.
4. Streamlined Application Processes and Increased Awareness
A persistent challenge with student loan forgiveness programs has been the complexity of the application process and a general lack of awareness among eligible borrowers. For 2026, a major focus is expected to be on streamlining these processes and significantly improving outreach.
This could involve creating a more centralized and user-friendly online portal for all federal forgiveness applications, pre-populating forms with existing federal data, and offering clear, step-by-step guidance. Increased funding for borrower outreach and counseling services is also anticipated, ensuring that more individuals understand their options and how to apply for student loan forgiveness 2026.
How New Federal Student Loan Forgiveness Programs in 2026 Could Erase Up to 10% of Your Debt
The 10% debt erasure figure is a compelling headline, and it’s important to understand how this could realistically play out for borrowers under the new 2026 programs. This percentage isn’t a universal across-the-board reduction for everyone, but rather a realistic outcome for many through a combination of enhanced IDR plans, expanded PSLF, and targeted initiatives.
Example Scenarios for 10% Debt Eradication:
- Lower-Balance Borrowers: For someone with an initial loan balance of $10,000 to $15,000, a new expedited forgiveness plan after 10 years of income-driven payments (compared to 20-25 years currently) could easily result in 10% or more of their original debt being forgiven much sooner than anticipated. If they’ve already been paying for several years, the remaining balance could be significantly reduced or eliminated.
- IDR Plan Enhancements: A borrower on an existing IDR plan with a high interest rate might find that the new, more generous discretionary income calculations lead to lower payments. Over time, these lower payments mean less principal is paid down, and a larger portion of the original loan balance remains to be forgiven at the end of the repayment term. If their original balance was $50,000 and the new IDR terms lead to $5,000 more being forgiven than under previous rules, that’s a 10% reduction.
- PSLF Expansion: A public servant who previously didn’t qualify for PSLF due to ambiguous employment definitions might now find themselves eligible. If they have accumulated several years of qualifying payments, the remaining balance on their loans could be forgiven, potentially representing a substantial portion, or even all, of their remaining debt. For someone with $30,000 remaining on a $50,000 original loan, a PSLF approval would be a 60% reduction of the original debt, far exceeding 10%. However, for others, it might be a 10% reduction of their original debt if they are close to the end of their payment period and have already paid a significant amount.
- Targeted Professional Forgiveness: A teacher in a high-need area might receive a new grant or forgiveness program specifically for their profession. If they have $40,000 in loans and a new program offers $4,000 in direct forgiveness, that’s exactly a 10% reduction.
The key takeaway is that these programs are designed to provide meaningful relief. For many, 10% of their original debt or current balance could be a very achievable and realistic outcome as a direct result of these upcoming changes. It’s about leveraging the right program for your specific situation.
Preparing for Student Loan Forgiveness 2026: Steps You Can Take Now
While 2026 might seem distant, proactive steps taken today can significantly improve your chances of benefiting from upcoming federal student loan forgiveness programs. Don’t wait for the official announcements; start organizing your financial life now.
1. Consolidate Federal Loans (if applicable)
Many federal student loan forgiveness programs, particularly PSLF and some IDR benefits, are exclusively available for Direct Loans. If you have older federal loans, such as FFEL Program loans or Perkins Loans, consolidating them into a Direct Consolidation Loan is often a necessary first step. This process can take time, so it’s wise to explore this option well in advance. Always consult with your loan servicer or a trusted financial advisor before consolidating, as it can sometimes reset your payment count for forgiveness programs.
2. Understand Your Loan Types and Servicer
Knowing exactly what type of federal loans you have is paramount. You can find this information by logging into your account on StudentAid.gov. This portal provides a comprehensive overview of your loan history, current servicer, and loan types. Different loan types qualify for different programs, so this is foundational knowledge. Your loan servicer is also a critical point of contact for questions and application processes.
3. Enroll in an Income-Driven Repayment (IDR) Plan
If you’re not already on an IDR plan, consider enrolling now. Many forgiveness programs require a history of payments under an IDR plan. By enrolling early, you start accumulating qualifying payments. Even if the IDR terms change in 2026, being on an existing plan often makes the transition to new, more favorable terms smoother. Regularly recertify your income and family size annually to ensure your payments are accurate and your account remains in good standing.
4. Explore Public Service Loan Forgiveness (PSLF) Eligibility
If you work for a government agency (federal, state, local, or tribal) or a qualifying non-profit organization, research the PSLF program. Use the PSLF Help Tool on StudentAid.gov to determine if your employer qualifies and to submit your Employment Certification Form (ECF) annually. Even if you’re unsure about student loan forgiveness 2026, consistently certifying your employment ensures that your payments are being tracked and counted towards the 120 required payments.
5. Keep Impeccable Records
Documentation is key to any successful loan forgiveness application. Maintain records of all loan statements, payment confirmations, correspondence with your loan servicer, and employment history (especially for PSLF). Digital copies are excellent, but also consider physical backups for crucial documents. This meticulous record-keeping will be invaluable when you apply for forgiveness, especially if there are discrepancies or disputes.
6. Stay Informed and Monitor Official Sources
The landscape of federal student aid and forgiveness is dynamic. Rely on official sources like StudentAid.gov, the Department of Education, and reputable financial news outlets for updates. Be wary of scams or third-party companies promising guaranteed forgiveness for a fee. Real federal programs will always be accessible directly through official channels and typically do not require payment for application assistance.
7. Consider Financial Counseling
If you feel overwhelmed or unsure about your options, consider seeking advice from a non-profit credit counselor or a certified financial planner. They can provide personalized guidance, help you understand your specific loan situation, and assist in developing a strategy to maximize your potential for student loan forgiveness 2026.
The Broader Impact of Student Loan Forgiveness in 2026
The potential for significant student loan forgiveness in 2026 extends beyond individual borrowers, promising a broader economic and social impact. Reducing the burden of student debt can unlock economic potential, foster greater equity, and improve the overall financial health of communities across the nation.
Economic Stimulus
When borrowers have less student debt, they have more disposable income. This can lead to increased consumer spending, which stimulates local economies. It can also free up funds for other major life investments, such as down payments on homes, starting businesses, or saving for retirement. This ripple effect can contribute to job creation and overall economic growth, making the case for student loan forgiveness 2026 not just a matter of individual relief but also national economic strategy.
Addressing Inequality
Student loan debt disproportionately affects certain demographic groups, particularly minority borrowers and those from lower socioeconomic backgrounds. Forgiveness programs, especially those that are income-driven or targeted, can help address these systemic inequalities. By reducing debt for those who struggle the most, these programs can foster greater economic mobility and reduce wealth gaps, creating a more equitable society.
Improved Mental and Physical Health
The stress associated with significant debt can take a heavy toll on mental and physical health. Studies have shown a strong correlation between financial stress and various health issues. By alleviating some of this burden, student loan forgiveness can contribute to improved well-being for millions of Americans, allowing them to focus more on their careers, families, and personal growth.
Strengthening the Workforce
Debt relief can also empower individuals to pursue careers in public service or other lower-paying but socially essential fields without the overwhelming pressure of high loan payments. This can strengthen critical sectors of the workforce, from education and healthcare to non-profit advocacy, benefiting society as a whole. The anticipated programs for student loan forgiveness 2026 are designed to reinforce these societal benefits.
Potential Challenges and Considerations
While the prospect of student loan forgiveness is exciting, it’s also important to acknowledge potential challenges and considerations. The implementation of large-scale federal programs is complex and can face various hurdles.
Political and Legislative Hurdles
Many of the anticipated changes and new programs will require legislative action or executive approval, which can be subject to political debate and shifts in policy priorities. The exact scope and eligibility criteria could evolve as these discussions progress. It’s crucial for borrowers to stay informed but also to manage expectations, understanding that the final outcomes may differ from initial proposals.
Administrative Complexity
Even with efforts to streamline processes, the sheer volume of borrowers and the complexity of different loan types and forgiveness programs can lead to administrative challenges. There may be delays in processing applications, and borrowers might need to be persistent in following up to ensure their applications are handled correctly. This underscores the importance of thorough documentation and proactive engagement with loan servicers.
Fiscal Impact
The cost of student loan forgiveness programs is a significant consideration for policymakers. Balancing the need for borrower relief with fiscal responsibility is a continuous challenge. The design of the 2026 programs will likely reflect these considerations, aiming for targeted relief that provides substantial benefits without undue strain on federal budgets.
Awareness and Education
Despite efforts to improve outreach, a significant challenge remains in ensuring that all eligible borrowers are aware of and understand how to access forgiveness programs. Many individuals may miss out on opportunities simply because they don’t know they exist or find the application process too daunting. Continued emphasis on public education and accessible resources will be vital for the success of student loan forgiveness 2026.
Conclusion: A Path Towards Greater Financial Freedom
The forthcoming federal student loan forgiveness programs in 2026 represent a significant opportunity for millions of Americans to achieve greater financial freedom. With potential enhancements to Income-Driven Repayment plans, expanded Public Service Loan Forgiveness, and new targeted initiatives, borrowers could see a meaningful reduction in their debt, with some potentially erasing up to 10% or more of their outstanding balances.
Understanding these programs, preparing proactively, and staying informed are your best strategies for capitalizing on these opportunities. By consolidating eligible loans, enrolling in IDR plans, tracking your PSLF eligibility, maintaining meticulous records, and monitoring official government sources, you can position yourself to benefit from the evolving landscape of student loan relief. The journey to financial liberation from student debt is often long and challenging, but with these new federal initiatives on the horizon, 2026 could mark a turning point for many, offering a renewed sense of hope and economic stability.