Federal Tax Reform 2026: Middle-Class Impact Analysis
Federal Tax Reform 2026: Middle-Class Impact Analysis
As the year 2026 looms closer, the discourse around potential federal tax reform is intensifying. For millions of middle-class households across the United States, understanding these proposed changes is not just an academic exercise; it’s a critical step in financial planning and securing their economic future. This comprehensive analysis delves into two prominent, competing federal tax reform proposals, dissecting their potential impacts on the backbone of the American economy: the middle class.
The current tax landscape, shaped by previous legislative actions, is set to undergo significant alterations. Many provisions are scheduled to expire, paving the way for new policies. This creates a fertile ground for various political factions and economic think tanks to put forth their visions for the future of federal tax reform. While the specifics of each proposal can be complex and laden with jargon, our aim here is to distill the essential elements and project their real-world consequences for middle-income earners.
The middle class, often defined by income levels, geographic location, and lifestyle, is a diverse group. Its members include teachers, small business owners, nurses, engineers, and countless others who form the engine of our society. Therefore, any significant federal tax reform will inevitably have a broad and varied ripple effect, touching everything from household budgets and savings to retirement plans and educational opportunities. Our comparison will highlight these nuanced impacts, allowing readers to gain a clearer picture of what 2026 might hold.
Understanding the Current Tax Environment and the Need for Federal Tax Reform
Before we dissect the proposed reforms, it’s crucial to grasp the existing tax framework and why federal tax reform is a perennial topic of discussion. The Tax Cuts and Jobs Act (TCJA) of 2017 introduced a series of significant changes, many of which are slated to expire at the end of 2025. These expirations include individual income tax rate reductions, increases in the standard deduction, and certain limitations on itemized deductions. Without new legislation, many taxpayers could face higher tax bills in 2026.
The impending expiration of these provisions serves as a primary catalyst for the current wave of federal tax reform proposals. Policymakers are faced with the challenge of either extending the existing provisions, allowing them to expire, or implementing entirely new tax structures. Each path carries distinct economic and social implications, particularly for the middle class. The debate often centers on issues of fairness, economic growth, and fiscal responsibility.
Furthermore, broader economic trends, such as inflation, wage stagnation, and wealth inequality, also contribute to the call for federal tax reform. Advocates for change argue that the current system may not adequately address these challenges or provide sufficient support for middle-income families. Understanding this context is vital for appreciating the motivations and potential consequences behind each proposal we will examine.
Proposal A: The ‘Economic Growth and Simplification’ Plan
One of the prominent proposals circulating for federal tax reform in 2026 can be characterized as the ‘Economic Growth and Simplification’ plan. This proposal typically advocates for lower overall tax rates, a simplified tax code, and incentives for business investment, with the underlying belief that these measures will stimulate the economy, create jobs, and ultimately benefit all income levels, including the middle class.
Key Features of Proposal A:
- Reduced Income Tax Brackets: This plan often suggests consolidating the current seven federal income tax brackets into fewer, broader brackets with lower marginal rates. For middle-class households, this could mean a direct reduction in their tax liability, especially for those currently near the top of their existing bracket.
- Increased Standard Deduction: To simplify filing and reduce the tax burden for many, Proposal A might advocate for an even higher standard deduction than currently exists, or at least an extension of the TCJA’s increased deduction. This would particularly benefit taxpayers who do not itemize, a common scenario for many middle-income families.
- Elimination or Caps on Certain Deductions: To offset the revenue loss from lower rates and higher standard deductions, this plan might propose eliminating or capping certain itemized deductions, such as state and local tax (SALT) deductions. While this could simplify the tax code, it might negatively impact middle-class homeowners in high-tax states.
- Business Tax Reductions: A core tenet of this proposal is often further reducing corporate income tax rates or providing additional tax incentives for businesses to invest and expand. The theory is that this will lead to higher wages and more employment opportunities for the middle class, though direct benefits can be debated.
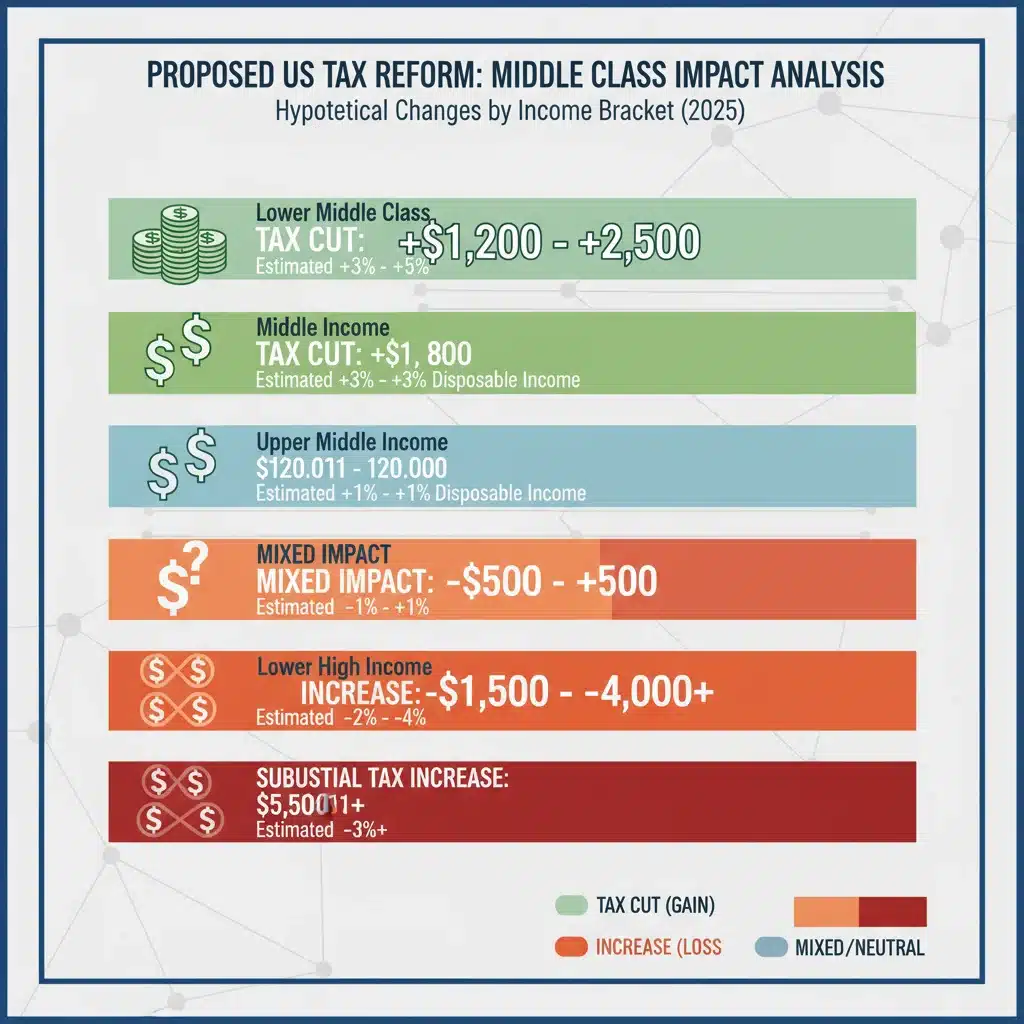
Projected Impact on Middle-Class Households under Proposal A:
For a significant portion of the middle class, particularly those who take the standard deduction and reside in states with lower property and income taxes, Proposal A could lead to a noticeable decrease in their federal income tax burden. The simplification aspect could also reduce the complexity and cost of tax preparation.
However, households with substantial itemized deductions, especially those in high-cost-of-living areas with high property taxes and state income taxes, might see their tax savings diminished or even face a slight increase if certain deductions are eliminated or capped. The long-term economic benefits, such as job creation and wage growth, are often cited as indirect positives for the middle class, but these are subject to broader economic factors.
For example, a middle-income family earning $100,000 annually, with a high mortgage interest deduction and significant state and local tax payments, might find the benefits of lower rates offset by the loss of certain deductions. Conversely, a similar family taking the standard deduction could see a clear financial gain. This highlights the varied impact of any federal tax reform on the diverse middle-class demographic.
Proposal B: The ‘Fairness and Investment’ Plan
The second major approach to federal tax reform for 2026 can be termed the ‘Fairness and Investment’ plan. This proposal generally emphasizes increasing taxes on higher earners and corporations to fund social programs, reduce income inequality, and invest in public infrastructure or other initiatives. The goal is often to create a more progressive tax system and ensure that the benefits of economic growth are more widely distributed, including to the middle class.
Key Features of Proposal B:
- Increased Tax Rates for High Earners: This plan typically advocates for raising the top marginal income tax rates, potentially adding new higher brackets for very high-income individuals. While not directly targeting the middle class, the revenue generated is often earmarked for programs that could indirectly benefit them.
- Expansion of Tax Credits for Middle and Lower Incomes: A cornerstone of this proposal is often the expansion or introduction of new refundable tax credits, such as an enhanced Child Tax Credit, Earned Income Tax Credit, or credits for childcare and education expenses. These direct financial benefits would be highly impactful for many middle-class families.
- Corporate Tax Adjustments: Rather than further reductions, Proposal B might suggest increasing the corporate income tax rate from its current level or implementing new taxes on corporate profits, especially those earned overseas. The argument is that corporations should contribute more to public services that benefit their workforce and consumers.
- Wealth or Capital Gains Adjustments: This plan might also include proposals to increase taxes on capital gains for high earners, adjust estate taxes, or even introduce new wealth taxes. These measures are designed to address wealth inequality, with potential indirect benefits for the middle class through increased public funding.
Projected Impact on Middle-Class Households under Proposal B:
For many middle-class households, particularly those with children or significant education/childcare costs, Proposal B could lead to a net increase in disposable income due to expanded tax credits. The focus on social programs and public investment could also provide indirect benefits through improved infrastructure, better public services, and potentially a stronger social safety net.
However, the indirect effects of increased corporate taxes or higher taxes on investment could be debated. Some economists argue that such measures could stifle economic growth, potentially leading to fewer jobs or slower wage increases, which could indirectly affect the middle class. Others contend that the benefits of increased public investment and reduced inequality outweigh these concerns.
Consider a middle-income family with two children. Under Proposal B, an enhanced Child Tax Credit could significantly reduce their overall tax burden or even provide a substantial refund, freeing up funds for essentials or savings. While their direct income tax rate might not change drastically, the credits could provide a powerful boost. The impact of this type of federal tax reform is often felt more through direct benefits and public services.
Comparing the Core Philosophies and Economic Ramifications of Federal Tax Reform
The fundamental difference between these two approaches to federal tax reform lies in their underlying economic philosophies. Proposal A leans towards supply-side economics, believing that lower taxes and deregulation for businesses and individuals will spur investment, innovation, and ultimately, broader prosperity. The benefits, proponents argue, will ‘trickle down’ to the middle class through job creation and wage growth.
Proposal B, on the other hand, aligns more with demand-side economics and progressive taxation principles. It posits that directly supporting middle and lower-income households through tax credits and public investments will boost demand, reduce inequality, and create a more stable and equitable economy. The revenue for these investments comes from those with the greatest ability to pay.
Economic Growth vs. Income Redistribution:
The debate around federal tax reform often boils down to this dichotomy. Proposal A prioritizes overall economic growth, hoping the middle class will benefit from a larger economic pie. Proposal B prioritizes a more equitable distribution of the existing pie and aims to grow it through public investment, ensuring the middle class has a larger slice.
The actual economic outcomes of either plan are complex and subject to numerous variables, including global economic conditions, technological advancements, and consumer behavior. Economic models can offer projections, but real-world results can vary. For the middle class, understanding which philosophy underpins a proposed federal tax reform is key to anticipating its potential effects.
Specific Impacts on Middle-Class Financial Pillars
Beyond the general tax burden, federal tax reform can have specific impacts on critical financial areas for middle-class households:
Savings and Investments:
- Retirement Accounts: Changes to tax-deferred retirement accounts (401(k)s, IRAs) or the taxation of withdrawals could significantly alter retirement planning for the middle class. Proposal A might favor policies that encourage more private savings, while Proposal B might look at ensuring equitable access to retirement vehicles.
- Capital Gains: While typically more relevant to higher earners, some middle-class households have investments. Changes to capital gains tax rates under Proposal B could affect long-term investment strategies. Proposal A would likely maintain or lower these rates to encourage investment.
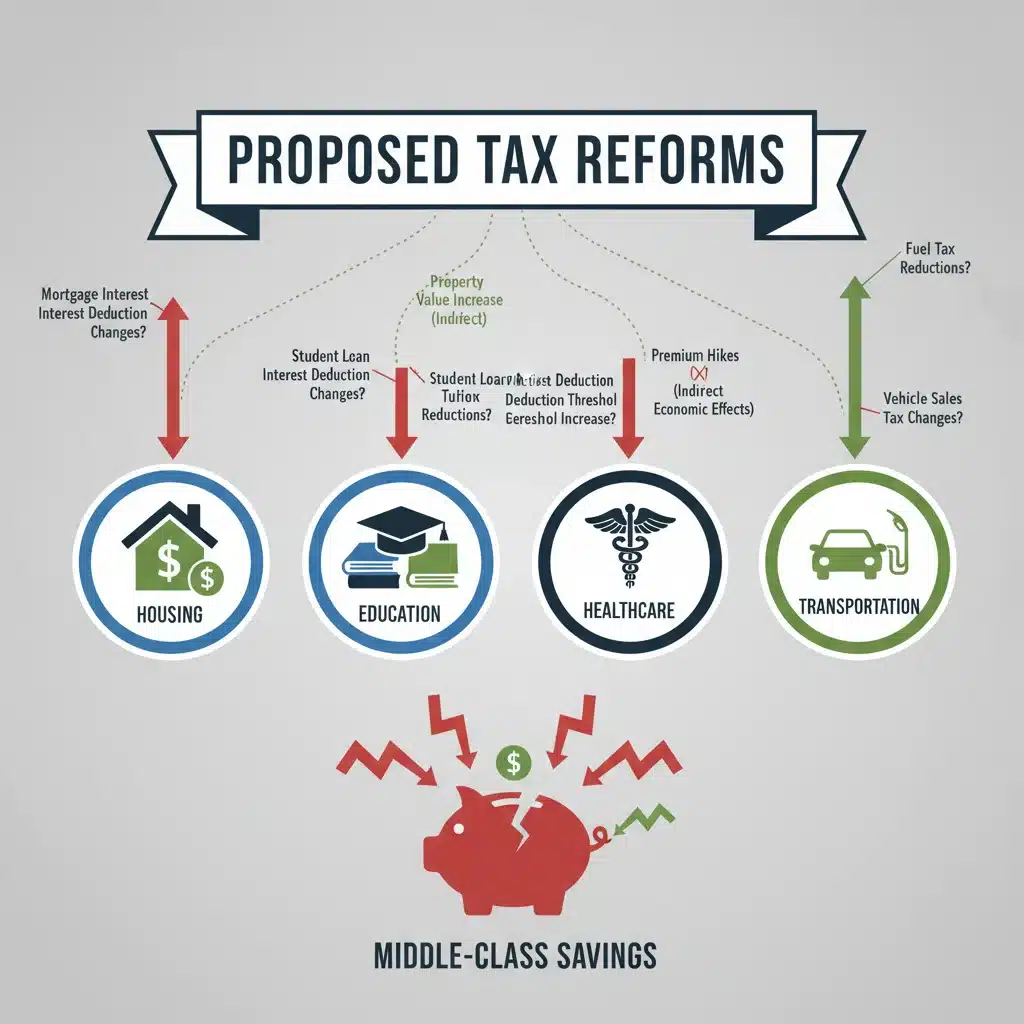
Housing and Homeownership:
- Mortgage Interest Deduction (MID): The MID is a significant benefit for many middle-class homeowners. While both proposals might retain some form of it, any changes to its limits or interaction with the standard deduction could be impactful. Proposal A might simplify, potentially reducing its utility for some, while Proposal B might use it as a targeted benefit.
- Property Taxes: The SALT deduction cap, a contentious issue, primarily affects homeowners in states with high property taxes. Proposal A might make the cap permanent or even lower it further, while Proposal B might advocate for its repeal or significant increase, providing relief to many middle-class homeowners.
Education and Childcare:
- Child Tax Credit (CTC): As mentioned, Proposal B is likely to expand the CTC, potentially making it fully refundable, which would be a direct financial boost for millions of middle-class families. Proposal A might maintain the current structure or make minor adjustments.
- Education Credits: Both plans could potentially modify existing education tax credits (e.g., American Opportunity Tax Credit, Lifetime Learning Credit) or introduce new ones, impacting college affordability for middle-class families.
- Childcare Deductions/Credits: The cost of childcare is a major burden. Proposal B would likely enhance existing credits or deductions, while Proposal A might focus on broader economic measures to indirectly lower costs.
The Political Landscape and Path to Federal Tax Reform
It’s important to remember that these proposals are not static; they are subject to intense political negotiation and compromise. The final version of any federal tax reform in 2026 will likely be a hybrid of various ideas, shaped by the prevailing political climate, the composition of Congress, and the priorities of the administration in power.
Interest groups, lobbyists, and public opinion will all play a significant role in influencing the outcome. Understanding the general direction of each proposal, however, allows middle-class households to anticipate potential changes and begin to plan accordingly.
Key Considerations for Policymakers:
- Revenue Neutrality: Will the proposed federal tax reform generate the same amount of revenue as the current system, or will it lead to a deficit or surplus?
- Economic Impact: How will the changes affect GDP growth, inflation, and employment rates?
- Fairness and Equity: How will the tax burden be distributed across different income levels and demographics?
- Simplicity: Will the new system be easier or harder for average taxpayers to understand and comply with?
These considerations are central to the debate and will ultimately determine the shape of the federal tax reform that takes effect in 2026. For the middle class, monitoring these discussions and understanding the potential trade-offs is crucial.
Preparing for the Future: What Middle-Class Households Can Do Now
While the exact contours of federal tax reform for 2026 remain uncertain, middle-class households can take proactive steps to prepare for potential changes:
Stay Informed:
Continuously follow reliable news sources and financial publications that track tax policy developments. Understanding the ongoing debate will help you anticipate which aspects of the proposals are gaining traction and which are falling by the wayside.
Review Your Financial Plan:
Periodically assess your current budget, savings, and investment strategies. Consider how different tax scenarios (e.g., higher or lower income tax rates, changes to deductions) might affect your net income and long-term financial goals. This is a crucial step for any household facing potential federal tax reform.
Consult a Tax Professional:
As 2026 approaches, speaking with a qualified tax advisor or financial planner can provide personalized insights. They can help you understand how proposed changes might specifically impact your unique financial situation and recommend strategies for optimization, especially concerning your approach to federal tax reform.
Maximize Current Tax Benefits:
Ensure you are fully utilizing all available tax deductions and credits under the current law. This includes maximizing contributions to tax-advantaged retirement accounts, taking advantage of education savings plans, and keeping meticulous records of deductible expenses. Being efficient with current tax laws can provide a buffer against future changes in federal tax reform.
Consider Your Location:
For those with flexibility, understanding how state and local taxes interact with federal proposals can be insightful. Changes to the SALT deduction, for instance, could make certain states more or less financially appealing for middle-class homeowners.
Conclusion: Navigating the Future of Federal Tax Reform
The impending federal tax reform in 2026 presents both challenges and opportunities for middle-class households. While the specifics of the final legislation are yet to be determined, understanding the two primary competing proposals – the ‘Economic Growth and Simplification’ plan and the ‘Fairness and Investment’ plan – provides a valuable framework for anticipation.
Each proposal carries a distinct philosophy and potential set of impacts, ranging from direct tax savings or increases to indirect effects on economic growth, social programs, and the cost of living. The middle class, with its diverse income levels and financial situations, will experience these changes in varied ways.
By staying informed, proactively reviewing personal finances, and seeking professional advice, middle-class families can better position themselves to navigate the evolving tax landscape. The goal is not just to react to federal tax reform but to strategically adapt and ensure continued financial well-being in the years to come. The future of taxation is dynamic, and preparedness is key to thriving through its shifts.