Federal Student Aid 2026: Unlock Over $120 Billion in Grants & Loans
The pursuit of higher education is a transformative journey, but for many, the financial burden can be a daunting hurdle. Thankfully, the U.S. Department of Education offers an extensive array of financial assistance programs designed to make college more accessible. With over $120 billion in federal student aid distributed annually, understanding and navigating the application process for federal student aid 2026 is paramount for prospective and current students. This comprehensive guide will equip you with the knowledge and strategies needed to maximize your chances of securing the funding you need.
Understanding Federal Student Aid 2026: More Than Just Loans
When people hear “federal student aid,” they often immediately think of loans. While federal student loans are a significant component, the umbrella of federal aid also includes substantial grants and work-study programs that do not need to be repaid. The key to unlocking these opportunities lies in completing the Free Application for Federal Student Aid (FAFSA).
What is Federal Student Aid?
Federal student aid comes from the U.S. government and helps students pay for tuition and fees, room and board, books and supplies, and transportation. It can be used for undergraduate or graduate studies at eligible colleges or career schools. The primary types of federal student aid include:
- Grants: Financial aid that doesn’t have to be repaid (e.g., Pell Grants, Federal Supplemental Educational Opportunity Grants – FSEOG).
- Loans: Money borrowed that must be repaid with interest (e.g., Direct Subsidized Loans, Direct Unsubsidized Loans, PLUS Loans).
- Work-Study: A program that allows students to earn money to help pay for educational expenses through part-time employment, usually on campus.
For the 2026-2027 academic year, the landscape of federal student aid continues to evolve, with ongoing efforts to simplify the FAFSA and expand eligibility. Staying informed about these changes is crucial for anyone planning their educational finances.
The FAFSA: Your Gateway to Federal Student Aid 2026
The FAFSA is the cornerstone of federal financial aid. It’s a free application that collects demographic and financial information to determine your eligibility for federal and, in many cases, state and institutional aid. Completing it accurately and on time is the single most important step in the process.
Key Changes and Simplifications to the FAFSA
The FAFSA has undergone significant overhauls in recent years, aiming to make it simpler and more accessible. While the 2024-2025 FAFSA saw major changes, the 2026-2027 FAFSA (which will open in late 2025) will continue to build on these improvements. Students and families can expect:
- Streamlined Application: Fewer questions and a more intuitive interface.
- Direct Data Exchange with IRS: For most applicants, financial data will be directly transferred from the IRS, reducing manual input and errors. This is a critical improvement for those seeking federal student aid 2026.
- Expanded Eligibility: Changes to the Student Aid Index (SAI), which replaced the Expected Family Contribution (EFC), are designed to make more students eligible for Pell Grants and other forms of aid.
These changes are designed to reduce barriers and ensure that more students, particularly those from low-income backgrounds, can access the financial support they need.
Who Should Complete the FAFSA?
Every student planning to attend college or career school, regardless of their family’s income level, should complete the FAFSA. Many students mistakenly believe their family earns too much money to qualify for aid. However, the FAFSA is not just for low-income students. It’s also required for:
- Unsubsidized Federal Student Loans: These loans are available to all eligible students, regardless of financial need.
- State Aid: Many states use FAFSA data to determine eligibility for their own financial aid programs.
- Institutional Aid: Most colleges and universities use FAFSA information to award their own scholarships and grants.
Even if you think you won’t qualify for need-based aid, completing the FAFSA opens the door to federal loans and other opportunities.
Critical Deadlines for Federal Student Aid 2026
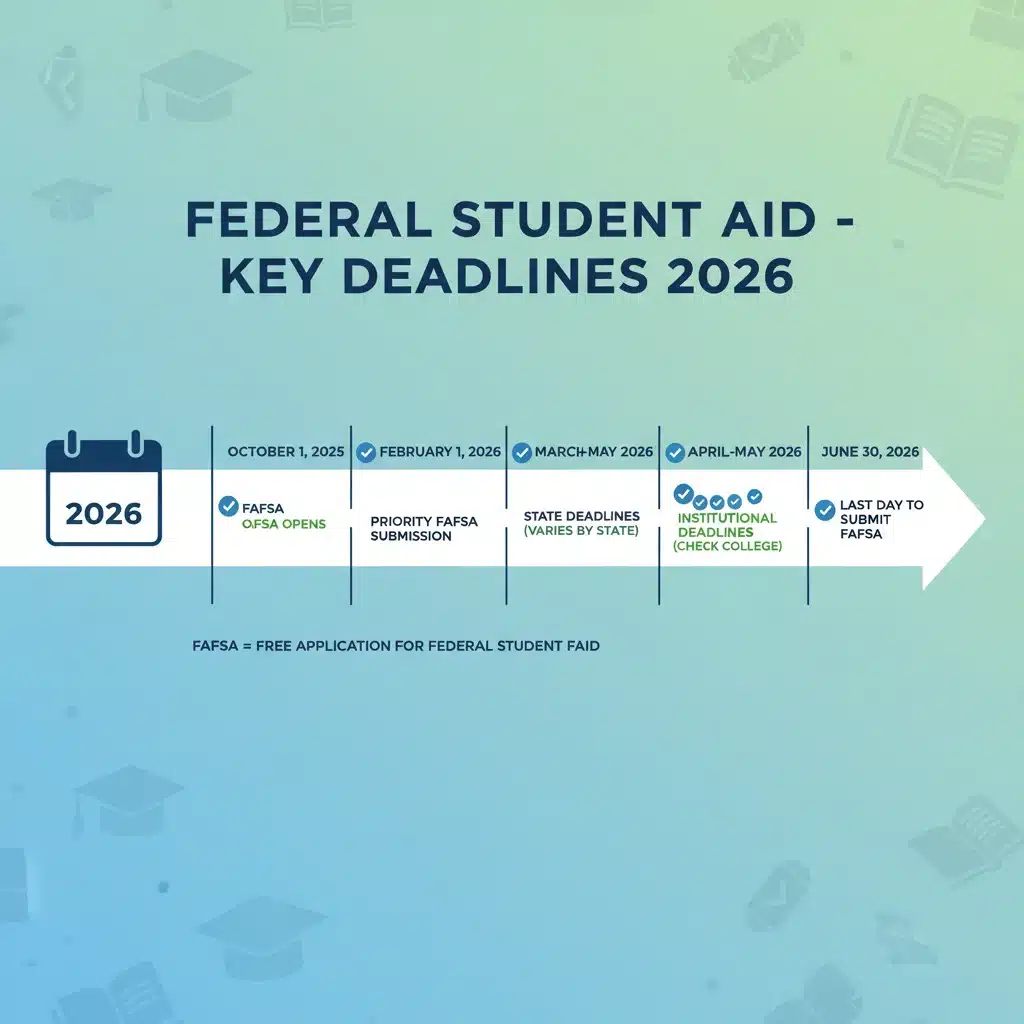
Missing a deadline can cost you thousands of dollars in financial aid. The application cycle for federal student aid 2026 (for the 2026-2027 academic year) typically opens in October of 2025. While the federal deadline is usually much later, state and institutional deadlines are often much earlier and can be crucial for maximizing your aid.
Federal FAFSA Deadline
The federal deadline for submitting the FAFSA for the 2026-2027 academic year will likely be June 30, 2027. However, this is the absolute last day, and by then, many state and institutional funds will have already been depleted.
State Deadlines
Many states have their own financial aid programs with much earlier FAFSA deadlines. Some states operate on a first-come, first-served basis, meaning that even if you meet the deadline, funds might run out. It’s imperative to check your state’s specific deadlines as early as possible. These can range from early fall (e.g., October, November) to spring (e.g., March) of 2026.
Institutional Deadlines
Colleges and universities also set their own deadlines for submitting the FAFSA and any additional institutional aid applications. These deadlines can vary significantly from school to school and are often tied to early admission or regular decision application dates. Always check the financial aid website of each school you are considering.
Pro Tip: Aim to complete your FAFSA as close to the opening date (likely October 1, 2025) as possible. This gives you the best chance to be considered for all available aid, especially those awarded on a first-come, first-served basis.
Eligibility for Federal Student Aid 2026
While completing the FAFSA is the first step, meeting basic eligibility requirements is also essential. Most students are eligible, but it’s good to be aware of the criteria.
Basic Eligibility Requirements:
- Be a U.S. citizen or an eligible noncitizen.
- Have a valid Social Security number (with some exceptions).
- Be enrolled or accepted for enrollment in an eligible degree or certificate program.
- Maintain satisfactory academic progress once in college.
- Sign statements on the FAFSA certifying that you will use federal student aid only for educational purposes and that you are not in default on any federal student loans or owe a refund on a federal grant.
- Be registered with Selective Service, if you are a male between the ages of 18 and 25.
Dependent vs. Independent Student Status
Your dependency status determines whose information you must report on the FAFSA. If you are considered a dependent student, you’ll need to provide information about your parents (or stepparents). If you are an independent student, you only need to provide your own information (and your spouse’s, if applicable).
The FAFSA asks a series of questions to determine dependency status. You are generally considered independent if you meet one or more of the following criteria:
- Are 24 years old or older by December 31 of the award year.
- Are married.
- Are working on a master’s or doctorate degree.
- Have children or other dependents who receive more than half of their support from you.
- Are an active duty member or veteran of the U.S. Armed Forces.
- Were in foster care at any time since turning age 13.
- Are an emancipated minor or in legal guardianship.
- Are experiencing homelessness or are at risk of homelessness.
If you have unusual circumstances that prevent you from providing parental information, even if the FAFSA determines you are dependent, you can speak to the financial aid office at your prospective college. They have the discretion to adjust your dependency status.
Maximizing Your Federal Student Aid 2026
Securing the most financial aid isn’t just about applying; it’s about strategic planning and understanding how the system works. Here are tips to maximize your aid package:
1. Submit Your FAFSA Early
As reiterated, this is the most critical advice. Many grants and some state aid are first-come, first-served. Submitting your FAFSA as soon as it opens (October 1, 2025, for the 2026-2027 aid year) significantly increases your chances of receiving more aid.
2. Be Accurate and Thorough
Errors on your FAFSA can delay processing or lead to a lower aid offer. Double-check all financial information, Social Security numbers, and dates. Use the IRS Direct Data Exchange whenever possible to minimize manual entry errors.
3. Understand the Student Aid Index (SAI)
The SAI is an index number that colleges use to determine how much federal student aid you are eligible to receive. It’s not the amount of money your family is expected to pay, but rather an eligibility index. A lower SAI generally means more financial need and potentially more aid. Understanding how assets and income affect your SAI can help you plan.
4. Consider All Types of Aid
Don’t just focus on grants. Federal student loans, especially subsidized ones, often have better terms and lower interest rates than private loans. Federal Work-Study can also provide valuable income and job experience.
5. Communicate with Financial Aid Offices
If your family’s financial situation has changed significantly since you filed your FAFSA (e.g., job loss, medical expenses), contact the financial aid office at your chosen schools. They may be able to make professional judgments to adjust your aid package.
6. Explore State and Institutional Aid
Beyond federal aid, states and individual colleges offer their own scholarships and grants. The FAFSA is often a prerequisite for these, but you may need to complete additional applications. Research these opportunities thoroughly.
A Closer Look at Federal Grants for 2026
Grants are the most desirable form of aid because they don’t have to be repaid. For federal student aid 2026, several key grant programs will be available:
Pell Grants
The Pell Grant is the largest federal grant program, primarily for undergraduate students with exceptional financial need. The maximum Pell Grant award amount changes annually. For the 2026-2027 academic year, expect the maximum award to be announced closer to the FAFSA opening date, potentially increasing from previous years. Eligibility is largely determined by your Student Aid Index (SAI).
Federal Supplemental Educational Opportunity Grants (FSEOG)
FSEOGs are for undergraduate students with exceptional financial need. Pell Grant recipients receive priority. Unlike Pell Grants, FSEOG funds are limited and distributed directly by colleges, so applying early is crucial.
Teacher Education Assistance for College and Higher Education (TEACH) Grants
The TEACH Grant program provides up to $4,000 per year to students who are completing coursework to begin a career in teaching and agree to teach in a high-need field in a low-income school for at least four years after graduation. If the service obligation is not met, the grant converts to an unsubsidized loan.
Iraq and Afghanistan Service Grants
These grants are for students who are not Pell Grant eligible but whose parent or guardian died as a result of military service in Iraq or Afghanistan after September 11, 2001. Specific eligibility criteria apply.
Navigating Federal Student Loans for 2026
If grants and scholarships don’t cover all your educational costs, federal student loans can bridge the gap. They offer significant advantages over private loans.
Direct Subsidized Loans
These loans are available to undergraduate students with demonstrated financial need. The U.S. Department of Education pays the interest on these loans while you are in school at least half-time, during your grace period, and during periods of deferment. This is a significant benefit.
Direct Unsubsidized Loans
These loans are available to undergraduate and graduate students regardless of financial need. The student is responsible for paying the interest during all periods. If you choose not to pay the interest while in school, it will accrue and be capitalized (added to your principal balance).
Direct PLUS Loans
These loans are for graduate or professional students (Grad PLUS) and parents of dependent undergraduate students (Parent PLUS) to help pay for education expenses not covered by other financial aid. Eligibility is not based on financial need, but a credit check is required. Borrowers with adverse credit histories may need an endorser.
Perkins Loans (Historically)
It’s important to note that the Federal Perkins Loan Program expired on September 30, 2017. While some institutions may still be servicing existing Perkins Loans, no new Perkins Loans are being disbursed for federal student aid 2026.
Advantages of Federal Loans:
- Fixed Interest Rates: Interest rates are fixed for the life of the loan.
- Income-Driven Repayment Plans: Options to adjust monthly payments based on your income and family size.
- Loan Forgiveness Programs: Opportunities for loan forgiveness under certain circumstances (e.g., Public Service Loan Forgiveness – PSLF).
- Deferment and Forbearance: Options to temporarily postpone payments if you face financial hardship.
Federal Work-Study Program for 2026
Federal Work-Study provides part-time jobs for undergraduate and graduate students with financial need, allowing them to earn money to help pay for educational expenses. The program encourages community service work and work related to your course of study.
- How it Works: Your school determines if you are eligible for Federal Work-Study. If you are, your financial aid award letter will indicate your eligibility. You then seek out and apply for available work-study jobs, often through your school’s career services or financial aid office.
- Payment: You are paid directly for hours worked, usually bi-weekly. Earnings do not count against your financial aid eligibility for the next academic year.
Preparing Your Documents for Federal Student Aid 2026
Even with the simplified FAFSA, having your documents ready will make the application process much smoother. For the 2026-2027 FAFSA, you will generally need:
- Your (and your parents’, if dependent) Social Security numbers.
- Your (and your parents’, if dependent) Alien Registration numbers if you are not a U.S. citizen.
- Your (and your parents’, if dependent) federal income tax returns from two years prior to the academic year. For the 2026-2027 FAFSA, this will be your 2024 tax information.
- Records of any other untaxed income (e.g., child support received, interest income, veterans noneducation benefits).
- Information on cash, savings, and checking account balances.
- Information on investments (e.g., real estate, mutual funds, stocks, other securities, trust funds, 529 plans, certificates of deposit).
- Information on business and farm assets (if applicable).
Having these documents organized before you begin the FAFSA will prevent delays and frustration.
After You Submit Your FAFSA: What to Expect
Submitting your FAFSA is a significant step, but the process doesn’t end there. Here’s what happens next:
1. FAFSA Submission Confirmation
You’ll receive a confirmation email once your FAFSA has been successfully submitted. Keep this for your records.
2. FAFSA Submission Summary (FSS)
Within a few days to a few weeks, you’ll receive a FAFSA Submission Summary (FSS), which replaces the Student Aid Report (SAR). This document summarizes the information you reported on your FAFSA and provides your Student Aid Index (SAI). Review it carefully for any errors. If you find mistakes, you’ll need to log back into your FAFSA and make corrections.
3. Aid Offers from Colleges
Once colleges receive your FAFSA information, they will begin to assemble financial aid packages. You’ll typically receive an award letter from each school you’ve been accepted to. These letters will detail the types and amounts of federal, state, and institutional aid you’ve been offered. Compare these offers carefully, considering the total cost of attendance and the types of aid (grants vs. loans).
4. Verification Process
Some students are selected for “verification.” This is a process where the financial aid office at your school requests additional documentation to confirm the information you reported on your FAFSA. Don’t be alarmed if you’re selected; it’s a routine procedure. Respond promptly to all requests to avoid delays in receiving your aid.
5. Accepting Your Aid
Once you’ve decided which school to attend, you’ll typically need to formally accept your financial aid offer through the school’s online portal. You can often accept or decline specific components of your aid package (e.g., you might accept grants but decline some or all of the loans).
Common Mistakes to Avoid When Applying for Federal Student Aid 2026
Even with a simplified FAFSA, mistakes can happen. Here are some common pitfalls to avoid:
- Not Filing the FAFSA: The most common mistake! Many eligible students miss out because they assume they won’t qualify.
- Missing Deadlines: State and institutional deadlines are often earlier than the federal deadline. Mark them on your calendar.
- Errors on the FAFSA: Incorrect Social Security numbers, birth dates, or financial figures can cause significant delays.
- Not Using the IRS Direct Data Exchange: Manually entering tax information increases the chance of errors. Use the IRS tool if available.
- Forgetting to Include Parent Information (if dependent): If you’re a dependent student, your parents’ financial information is required.
- Not Reviewing the FAFSA Submission Summary (FSS): Always review your FSS for accuracy and make corrections if needed.
- Not Communicating Changes: If your financial situation changes after filing, inform your school’s financial aid office.
- Only Applying for Federal Aid: Remember to also seek out state, institutional, and private scholarships.
The Long-Term Impact of Federal Student Aid
Accessing federal student aid 2026 isn’t just about covering immediate college costs; it’s an investment in your future. Grants reduce the amount you need to borrow, directly lowering your post-graduation debt burden. Federal loans, with their favorable terms and repayment options, provide a safer and more manageable alternative to private loans.
By understanding the process, meeting deadlines, and leveraging all available resources, you can significantly reduce the financial stress associated with higher education, allowing you to focus on your studies and achieve your academic and career goals. The $120 billion allocated for federal student aid is there to support you; your task is to successfully navigate the path to secure it.
Conclusion: Plan Early, Apply Smart, Succeed Financially
The journey to higher education is an exciting one, and financial aid plays a crucial role in making it a reality for millions of students. For federal student aid 2026, the message is clear: plan early, apply smart, and stay informed. The simplified FAFSA, coupled with the vast resources available through federal grants, loans, and work-study programs, offers unparalleled opportunities to fund your college education.
Begin preparing in advance of the FAFSA opening in October 2025. Gather your documents, understand the deadlines for your chosen states and institutions, and don’t hesitate to reach out to financial aid professionals if you have questions. By taking these proactive steps, you can confidently pursue your educational aspirations, knowing that you’ve maximized your chances of receiving the financial support you deserve.
Remember, an investment in education is an investment in yourself, and federal student aid is designed to help you make that investment without overwhelming financial strain. Good luck!