2026 Retirement Contribution Limits: What You Need to Know (RECENT UPDATES)
In the dynamic world of financial planning, staying informed about the latest changes in retirement contribution limits is paramount. As we look ahead to 2026, it’s crucial for individuals and families to understand how these adjustments can impact their long-term financial security. The Internal Revenue Service (IRS) periodically updates these limits to account for inflation and other economic factors, and these changes can significantly influence how much you can save for retirement each year. This comprehensive guide will delve into the anticipated 2026 retirement limits, offering insights, strategies, and practical advice to help you maximize your retirement savings.
Retirement planning is not a one-size-fits-all endeavor. It requires careful consideration of various factors, including your age, income, financial goals, and risk tolerance. Understanding the specific contribution limits for different retirement accounts – such as 401(k)s, IRAs, Roth IRAs, and other plans – is a foundational step in building a robust retirement strategy. Ignoring these updates could mean missing out on valuable tax advantages and the opportunity to accelerate your savings growth. Therefore, being proactive and informed about the 2026 retirement limits is an essential component of sound financial management.
Understanding the Basics: Why Contribution Limits Change
Before diving into the specifics of the 2026 retirement limits, it’s helpful to understand why these limits change in the first place. The IRS, in conjunction with other government agencies, reviews economic data annually to determine appropriate adjustments to retirement plan contribution limits. The primary driver for these changes is inflation, as measured by indices like the Consumer Price Index (CPI). When inflation rises, the cost of living increases, and consequently, the amount of money needed for retirement also goes up. To help individuals keep pace with these rising costs and maintain their purchasing power in retirement, the IRS adjusts the contribution limits upwards.
These adjustments are not arbitrary; they are part of a broader strategy to encourage saving for retirement and to ensure that the tax benefits associated with these accounts remain relevant and effective. By increasing the amount individuals can contribute, the government aims to provide greater incentives for long-term financial planning. This also helps to ensure that retirement plans continue to serve their purpose of providing a secure financial future for retirees. Therefore, when you see changes in the 2026 retirement limits, it’s a reflection of ongoing economic shifts and a governmental effort to support your financial well-being.
Beyond inflation, other factors can influence these limits, including legislative changes and specific provisions within the tax code. For example, laws like the SECURE Act and SECURE 2.0 Act have introduced significant modifications to retirement planning rules, including catch-up contribution provisions and required minimum distribution (RMD) ages. While the 2026 retirement limits primarily reflect inflation adjustments, it’s always wise to be aware of any broader legislative changes that might also impact your retirement strategy. Staying informed about these underlying mechanisms will empower you to make more strategic decisions regarding your retirement savings.
Anticipated 2026 Retirement Limits for 401(k) and Similar Plans
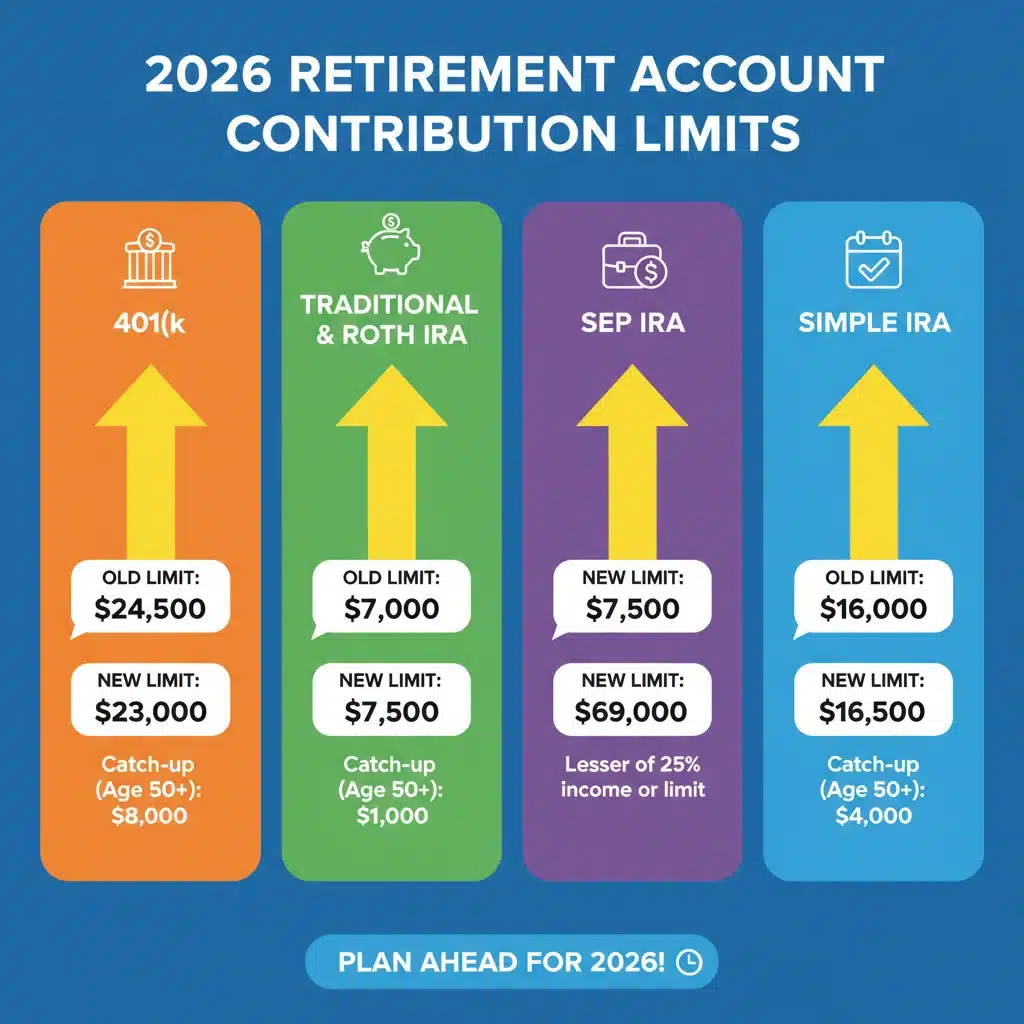
The 401(k) is arguably one of the most popular employer-sponsored retirement plans, offering significant tax advantages and often matching contributions from employers. For many, it forms the cornerstone of their retirement savings strategy. While the official 2026 retirement limits won’t be formally announced until late 2025, we can project potential increases based on historical trends and current inflationary pressures. Typically, the 401(k) contribution limit sees an increase of $500 to $1,000 annually, depending on economic conditions.
For 2026, it is highly probable that the elective deferral limit for employees contributing to 401(k), 403(b), most 457 plans, and the Thrift Savings Plan (TSP) will see an increase. If inflation continues at a moderate pace, we could anticipate the limit rising to approximately $24,000 or even $24,500. This would represent a substantial opportunity for individuals to set aside more pre-tax income, reducing their current taxable income while simultaneously boosting their retirement nest egg. Maximizing your 401(k) contributions, especially if your employer offers a match, is often considered one of the smartest financial moves you can make.
Furthermore, the catch-up contribution limit for those aged 50 and over is also subject to annual adjustments. This provision allows older workers to contribute an additional amount beyond the standard limit, recognizing that they may have less time to save for retirement. For 2026, we can expect this catch-up limit to also see an increase, potentially moving towards $8,000 or more. This is a critical feature for individuals nearing retirement who may be looking to supercharge their savings in their final working years. Keeping an eye on these specific 2026 retirement limits for catch-up contributions is essential for older savers.
It’s important to remember that these are projections. The actual 2026 retirement limits will be officially released by the IRS in the fall of 2025. However, planning based on reasonable estimates allows you to prepare your budget and contribution strategy in advance. Many financial advisors recommend aiming to contribute at least enough to receive any employer match, and then, if feasible, trying to reach the maximum allowable contribution. This strategy ensures you’re taking full advantage of all available tax-deferred growth opportunities.
IRA and Roth IRA Contribution Limits for 2026
Individual Retirement Arrangements (IRAs) and Roth IRAs are popular choices for individuals who may not have access to an employer-sponsored plan, or who wish to supplement their existing workplace savings. These accounts offer different tax treatments – traditional IRAs offer tax-deductible contributions and tax-deferred growth, while Roth IRAs feature after-tax contributions and tax-free withdrawals in retirement. Both are subject to annual contribution limits, which are also expected to see adjustments for 2026.
Based on current economic forecasts and historical patterns, the standard IRA and Roth IRA contribution limit for 2026 is likely to increase. We could anticipate this limit moving from the current levels to approximately $7,500 or $8,000. This increase, while seemingly modest compared to 401(k) limits, can still have a significant impact on your long-term savings, especially when compounded over many years. For those who contribute the maximum allowable amount, even a small increase in the limit translates to more money growing tax-advantaged for their future.
Similar to 401(k)s, IRAs also have catch-up contribution provisions for individuals aged 50 and over. This allows older savers to contribute an additional amount each year. For 2026, it’s reasonable to expect this catch-up limit for IRAs to also increase, potentially reaching $1,500 or more above the standard limit. This provision is particularly beneficial for those who started saving later in life or who are looking to make up for periods of lower contributions. Understanding these specific 2026 retirement limits for IRAs and Roth IRAs is key to optimizing your personal retirement savings.
It’s also important to remember that Roth IRA contributions come with income limitations. If your modified adjusted gross income (MAGI) exceeds certain thresholds, your ability to contribute directly to a Roth IRA may be phased out or eliminated. These income thresholds are also adjusted annually for inflation. While we don’t have the precise 2026 retirement limits for these income thresholds yet, it’s safe to assume they will also see an upward adjustment, potentially allowing more individuals to qualify for direct Roth IRA contributions. If you find yourself above the direct contribution limits, strategies like the ‘backdoor Roth IRA’ may still be an option, but it’s always best to consult with a financial advisor to navigate these complexities.
Other Retirement Plans and Their Projected 2026 Limits
Beyond 401(k)s and IRAs, several other retirement vehicles cater to specific needs, particularly for self-employed individuals and small business owners. These include SEP IRAs, SIMPLE IRAs, and Solo 401(k)s. The 2026 retirement limits for these plans are also subject to annual adjustments based on inflation and other factors, and understanding them is vital for those who utilize these options.
SEP IRA Contribution Limits (Simplified Employee Pension)
A SEP IRA is an employer-sponsored retirement plan primarily used by self-employed individuals and small business owners. Contributions are made solely by the employer (even if the employer is the business owner themselves) and are tax-deductible. The maximum contribution to a SEP IRA is generally capped at 25% of an employee’s compensation (or net earnings from self-employment) or a specified dollar amount, whichever is less. For 2026, we anticipate an increase in this dollar amount. Based on projections, the maximum contribution could rise to approximately $69,000 or $70,000, up from previous years. This allows significant tax-deferred savings for high-income self-employed individuals.
SIMPLE IRA Contribution Limits (Savings Incentive Match Plan for Employees)
SIMPLE IRAs are another option for small businesses, offering a simpler administrative structure than 401(k)s. Both employees and employers can contribute to a SIMPLE IRA. Employee contributions are subject to an annual limit, which is expected to increase for 2026. Projections suggest the employee contribution limit might reach around $17,000 or $17,500. Additionally, the catch-up contribution limit for those aged 50 and over is also likely to see an increase, potentially moving towards $4,000 or more. These increases in the 2026 retirement limits for SIMPLE IRAs will provide more flexibility for small business employees to save.
Solo 401(k) Contribution Limits
The Solo 401(k), also known as an individual 401(k) or one-participant 401(k), is an excellent choice for self-employed individuals or business owners with no full-time employees other than themselves or their spouse. It allows for contributions as both an employee and an employer, offering the potential for very high contribution limits. The employee elective deferral limit for a Solo 401(k) will align with the standard 401(k) limit, which, as discussed, is projected to be around $24,000-$24,500 for 2026. The catch-up contribution for those 50 and older will also apply. Furthermore, the employer contribution component, which can be up to 25% of compensation, combined with the employee contribution, means the total contribution limit (excluding catch-up) could exceed $69,000 or $70,000 for 2026. This makes the Solo 401(k) an extremely powerful tool for maximizing retirement savings for eligible individuals, especially with the increased 2026 retirement limits.
Strategies to Maximize Your Savings with the New 2026 Retirement Limits
Knowing the 2026 retirement limits is one thing; effectively utilizing them is another. Here are several strategies to help you maximize your retirement savings in light of the upcoming changes:
- Automate Your Contributions: Set up automatic transfers from your paycheck or bank account to your retirement plans. This ‘set it and forget it’ approach ensures consistent contributions and helps you reach the maximum limits without having to actively remember each month. When the 2026 retirement limits are announced, adjust your automatic contributions accordingly.
- Prioritize Employer Match: If your employer offers a matching contribution to your 401(k) or similar plan, always contribute at least enough to receive the full match. This is essentially free money and provides an immediate, guaranteed return on your investment. Failing to do so means leaving money on the table.
- Utilize Catch-Up Contributions: If you are aged 50 or older, make sure to take advantage of the catch-up contribution provisions for your 401(k) and IRA. These additional amounts can significantly boost your savings in the years leading up to retirement, especially with the projected increases in 2026 retirement limits.
- Diversify Your Retirement Accounts: Don’t put all your eggs in one basket. Consider contributing to both a traditional 401(k)/IRA and a Roth IRA if your income allows. This provides tax diversification in retirement, giving you more flexibility to manage your tax burden depending on future tax rates.
- Review Your Budget Annually: As the 2026 retirement limits come into effect, take time to review your household budget. Look for areas where you can cut expenses and reallocate those funds to your retirement accounts. Even small adjustments can add up over time.
- Consider a Health Savings Account (HSA): While not strictly a retirement account, an HSA offers a triple tax advantage (tax-deductible contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses). After age 65, funds can be withdrawn for any purpose, taxed as ordinary income, essentially acting as an additional retirement savings vehicle. HSAs also have annual contribution limits that adjust for inflation, which you should monitor alongside the 2026 retirement limits.
- Consult a Financial Advisor: For complex financial situations or if you’re unsure how to best utilize the new limits, a qualified financial advisor can provide personalized guidance. They can help you create a comprehensive retirement plan tailored to your specific goals and circumstances, ensuring you make the most of the 2026 retirement limits and other financial opportunities.
Impact of Inflation and Economic Factors on 2026 Retirement Limits
The adjustments to the 2026 retirement limits are a direct response to prevailing economic conditions, particularly inflation. Understanding this relationship can help you anticipate future changes and plan more effectively. When inflation is high, the purchasing power of money diminishes. This means that a dollar saved today will be worth less in the future. By increasing contribution limits, the IRS attempts to counteract this effect, allowing individuals to save more dollars that can grow and potentially maintain their value over time.
For example, if the cost of goods and services rises by 3% annually, and your retirement savings are not growing at a comparable rate, your future purchasing power will be eroded. The increased 2026 retirement limits provide an opportunity to inject more capital into tax-advantaged accounts, where it can grow through investments, ideally outpacing inflation. This is why it’s not just about contributing, but also about investing those contributions wisely.
Beyond inflation, other economic factors can play a role. Wage growth, for instance, can influence how much individuals are able to save. Strong wage growth often correlates with higher disposable income, making it easier for people to meet or even exceed the new 2026 retirement limits. Conversely, periods of economic stagnation or recession might lead to more modest increases in limits, or even a pause in adjustments, though this is less common for retirement contributions due to the long-term nature of these plans.
It’s also worth noting that the specific formulas used by the IRS to calculate these adjustments can be complex, often involving rounding rules that can sometimes lead to limits remaining flat for a year if the calculated increase doesn’t meet a certain threshold. However, given recent inflationary trends, it’s highly probable that we will see meaningful increases across most retirement plan limits for 2026. Staying informed about these broader economic indicators can give you an edge in anticipating and adapting to future changes in the 2026 retirement limits and beyond.
Don’t Forget About Employer-Sponsored Pensions and Other Plans
While 401(k)s and IRAs often dominate the conversation around retirement savings, it’s important not to overlook other valuable plans, particularly for those working in public service or for certain non-profit organizations. These include 403(b) plans, 457 plans, and traditional pension plans.
403(b) Plans
Similar to 401(k)s, 403(b) plans are available to employees of public schools and certain tax-exempt organizations. The elective deferral limits for 403(b)s typically mirror those of 401(k)s. Therefore, the projected increases in the 2026 retirement limits for 401(k)s (e.g., to $24,000-$24,500) will also apply to 403(b) plans. These plans also often include special catch-up provisions for long-term employees, allowing even higher contributions in their later years of service. It’s crucial for eligible individuals to consult their plan administrators to understand all available contribution options.
457 Plans
457 plans are deferred compensation plans available to state and local government employees, as well as some non-governmental tax-exempt organizations. One unique advantage of 457 plans is that their contribution limits are separate from 401(k)s and 403(b)s, meaning an individual could potentially contribute the maximum to both a 401(k) and a 457 plan in the same year. The elective deferral limits for 457 plans are also expected to align with the 401(k) and 403(b) limits for 2026, reaching approximately $24,000-$24,500. Furthermore, 457 plans have unique catch-up provisions, allowing participants nearing retirement to contribute double the annual limit in the three years prior to their normal retirement age, which is distinct from the age 50 catch-up. This makes 457 plans incredibly powerful for maximizing savings, especially with the anticipated 2026 retirement limits.
Pension Plans (Defined Benefit Plans)
While less common in the private sector today, many public sector employees still benefit from defined benefit pension plans. These plans promise a specific payout in retirement, often based on years of service and salary, rather than relying on individual contributions and investment performance. While there aren’t ‘contribution limits’ in the same way as defined contribution plans, there are limits on the maximum annual benefit that can be paid from a defined benefit plan. These limits are also adjusted for inflation annually, and we can expect a slight increase for 2026. Although you don’t directly contribute to these limits, understanding them is part of a holistic view of your retirement income, alongside the 2026 retirement limits for your other accounts.
The Importance of Early and Consistent Saving
Regardless of the specific 2026 retirement limits, the fundamental principle of retirement planning remains the same: the earlier you start saving and the more consistently you contribute, the greater your chances of achieving a comfortable retirement. The power of compounding interest is a financial marvel; even modest contributions made early in your career can grow into substantial sums over decades.
For instance, a 25-year-old who contributes $200 per month to a retirement account earning an average annual return of 7% could accumulate over $500,000 by age 65. If that same individual waits until age 35 to start, they would need to contribute significantly more each month to reach the same goal. The increases in the 2026 retirement limits provide an even greater opportunity for early savers to get a head start, allowing more of their money to benefit from tax-advantaged growth for a longer period.
Consistency is equally vital. Life happens, and there will be times when financial pressures make it tempting to pause or reduce retirement contributions. However, even small, consistent contributions during challenging times are better than no contributions at all. Re-evaluating your contributions annually, especially when new 2026 retirement limits are announced, helps ensure you’re always on track and taking full advantage of the updated opportunities.
Moreover, consistent saving instills financial discipline, which extends beyond retirement planning to other areas of your financial life. It helps build an emergency fund, manage debt, and achieve other short-term and long-term financial goals. Viewing the 2026 retirement limits not just as ceilings, but as targets to aim for, can be a powerful motivator in your financial journey.
Conclusion: Preparing for Your Financial Future with 2026 Retirement Limits
The upcoming 2026 retirement limits represent a significant opportunity for individuals to refine and optimize their retirement savings strategies. By staying informed about these changes, understanding the various retirement account options, and implementing smart saving strategies, you can significantly enhance your financial security in retirement.
Remember that these limits are designed to help you save more effectively, taking into account the realities of inflation and the evolving economic landscape. Don’t let the complexity deter you; instead, view these updates as an invitation to review your current financial plan and make necessary adjustments. Whether you’re maximizing your 401(k) contributions, leveraging catch-up provisions, or exploring specialized plans like SEP or Solo 401(k)s, each decision contributes to a more robust retirement nest egg.
As the official IRS announcements draw closer in late 2025, remain vigilant for the confirmed 2026 retirement limits. In the meantime, use the projections discussed in this article to begin strategizing. Consult with a financial advisor to create a personalized plan that aligns with your financial goals and takes full advantage of every opportunity presented by these new limits. Your future self will thank you for the diligence and foresight you exercise today in preparing for a comfortable and secure retirement.