Unlocking Your Financial Potential: Comparing High-Yield Savings Accounts with 5.25% APY for Your 2026 Goals
In today’s dynamic financial landscape, simply stashing your money in a traditional savings account is akin to leaving potential growth on the table. For savvy individuals and families looking to maximize their earnings and achieve their financial milestones by 2026, high-yield savings accounts (HYSAs) have emerged as a powerful tool. Specifically, finding a high-yield savings account offering a competitive 5.25% APY can significantly accelerate your progress towards goals like a down payment on a home, a dream vacation, or a robust emergency fund. This comprehensive guide will delve into the world of high-yield savings accounts, compare top contenders offering enticing rates, and equip you with the knowledge to make an informed decision that aligns with your 2026 aspirations.
What Exactly Are High-Yield Savings Accounts?
Before we dive into specific comparisons, let’s clarify what defines a high-yield savings account. Unlike conventional savings accounts that often offer paltry interest rates, HYSAs are designed to provide significantly higher Annual Percentage Yields (APYs). This higher return is typically achieved because these accounts are often offered by online-only banks or fintech companies that have lower overhead costs compared to traditional brick-and-mortar institutions. These savings are then passed on to consumers in the form of better interest rates.
The core benefit of a high-yield savings account is that your money grows faster due to compounding interest. This means you earn interest not only on your initial deposit but also on the accumulated interest from previous periods. Over time, especially with a strong APY like 5.25%, this compounding effect can lead to substantial growth in your savings, making your money work harder for you.
Why Aim for a 5.25% APY High-Yield Savings Account?
The 5.25% APY mark is a particularly attractive target for several reasons. Firstly, it represents a significant premium over the national average for savings accounts, which often hovers well below 1%. This difference can translate into hundreds, if not thousands, of extra dollars earned over a few years, directly impacting your ability to reach your 2026 financial goals.
Secondly, a 5.25% APY offers a strong defense against inflation. While inflation can erode the purchasing power of your money, a high-yield savings account with a competitive rate helps your savings keep pace, or even outpace, rising costs. This preserves the real value of your money, ensuring your future goals remain attainable.
Finally, securing such a rate demonstrates a proactive approach to personal finance. It shows you’re committed to optimizing your savings strategy and leveraging the best tools available to build wealth. For anyone planning for a specific future event, whether it’s a down payment, retirement supplement, or a child’s education fund, a 5.25% APY high-yield savings account provides a robust foundation.
Key Factors to Consider When Comparing High-Yield Savings Accounts
While a high APY is undoubtedly a crucial factor, it’s not the only consideration when choosing a high-yield savings account. A holistic approach involves evaluating several other aspects to ensure the account truly meets your needs. Here are the most important factors to keep in mind as you compare options:
1. Annual Percentage Yield (APY)
Naturally, the APY is paramount. Always compare the stated APY, but also understand that these rates can be variable and subject to change based on market conditions, particularly the federal funds rate. Look for banks that have a history of offering consistently competitive rates. Some banks might offer promotional rates for a limited time, so be sure to read the fine print and understand what the rate will revert to after the promotional period.
2. Minimum Balance Requirements
Some high-yield savings accounts require a minimum initial deposit or a minimum ongoing balance to earn the advertised APY or to avoid monthly fees. Ensure that you can comfortably meet these requirements without stretching your finances. If you fall below the minimum, you might either earn a lower interest rate or incur fees, negating the benefits of the high yield.
3. Monthly Fees
The goal of a high-yield savings account is to earn money, not to pay it out in fees. Most reputable online HYSAs have no monthly maintenance fees, especially if you meet certain criteria (e.g., maintain a minimum balance or set up direct deposit). Always verify the fee structure to ensure there are no hidden charges that could eat into your earnings.
4. FDIC Insurance
This is non-negotiable. Ensure that any bank you choose is insured by the Federal Deposit Insurance Corporation (FDIC). FDIC insurance protects your deposits up to $250,000 per depositor, per insured bank, for each account ownership category, providing peace of mind that your money is safe, even if the bank fails.
5. Accessibility and Transfer Options
Consider how easily you can access your funds or transfer money between accounts. Most online HYSAs offer convenient online and mobile banking platforms. Look for features like:
- Easy linking to external bank accounts for transfers.
- Availability of mobile check deposit.
- ATM access (though less common for pure savings accounts, some may offer it).
- Speed of transfers (e.g., same-day vs. 2-3 business days).
While savings accounts are not designed for frequent transactions, you’ll want to ensure you can move your money when needed without undue hassle.
6. Customer Service
Even with online banks, reliable customer service is crucial. Check for available support channels (phone, email, chat), hours of operation, and read reviews about their responsiveness and helpfulness. A smooth banking experience often hinges on efficient support when you encounter an issue.
7. Mobile Banking Experience
In our increasingly digital world, a user-friendly mobile app is essential. A good app allows you to easily check balances, view transactions, transfer funds, and manage your account on the go. Read reviews of the bank’s mobile app in app stores to gauge its functionality and user satisfaction.
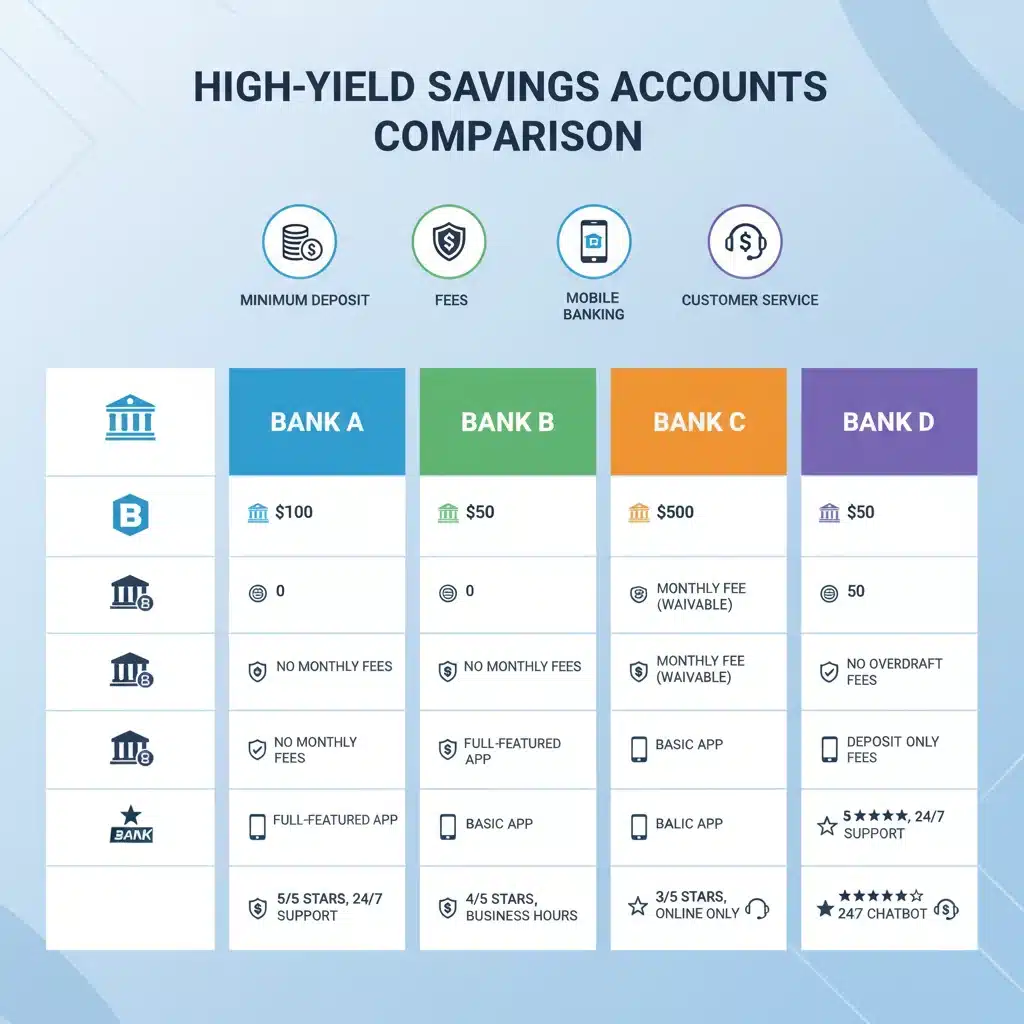
Top Contenders for High-Yield Savings Accounts with 5.25% APY (or Similar) for 2026 Goals
While specific rates can fluctuate, several online banks consistently offer some of the most competitive high-yield savings accounts. It’s important to note that a precise 5.25% APY might not always be available from every bank simultaneously, as rates are dynamic. However, these institutions are known for being at the forefront of offering strong rates and are excellent places to start your search for a high-yield savings account that meets or exceeds this target.
Bank A: The Digital Innovator
- Pros: Often features among the highest APYs, no monthly fees, no minimum balance to open, excellent mobile app, 24/7 customer support.
- Cons: Purely online, so no physical branches. Transfers to external banks might take a couple of business days.
- Ideal for: Tech-savvy savers comfortable with digital banking, who prioritize maximizing their interest earnings and don’t need branch access.
- Why it’s great for 2026 goals: Its consistently high APY ensures your savings grow rapidly, directly contributing to your long-term objectives.
Bank B: The Established Online Powerhouse
- Pros: Consistently competitive rates, strong reputation, robust online platform, minimal fees, good customer service.
- Cons: May require a small minimum deposit to earn the absolute highest APY tier.
- Ideal for: Savers looking for a reliable, well-established online bank with a proven track record of competitive rates and solid features.
- Why it’s great for 2026 goals: Its stability and competitive APY provide a secure and lucrative home for your funds, helping you steadily build towards your future.
Bank C: The Flexible Option
- Pros: Good APY, no minimum balance, no monthly fees, offers some ATM access through partnerships, user-friendly interface.
- Cons: APY might occasionally trail the absolute top competitors by a small margin.
- Ideal for: Individuals who appreciate some flexibility with ATM access and a straightforward online banking experience, without sacrificing a strong yield.
- Why it’s great for 2026 goals: The combination of a strong APY and accessible features makes it a practical choice for those who might need occasional access to their savings without penalties.
Bank D: The Hybrid Model
- Pros: Competitive APY, potentially offers some limited branch access through parent company affiliations, strong customer support.
- Cons: May have slightly higher minimum balance requirements to unlock the best rates.
- Ideal for: Savers who prefer a blend of online convenience with the reassurance of a larger financial institution, even if physical access is limited.
- Why it’s great for 2026 goals: Provides a bridge between traditional and online banking, offering competitive growth while potentially easing concerns for those less accustomed to purely digital platforms.
Disclaimer: Interest rates are subject to change without notice. Always check the current APY and terms directly on the bank’s website before opening an account. The banks listed above are examples of types of institutions that typically offer competitive high-yield savings accounts and are not specific recommendations for current rates.
Strategies for Maximizing Your High-Yield Savings Account for 2026
Simply opening a high-yield savings account is the first step; strategically utilizing it is key to hitting your 2026 goals. Here are some effective strategies:
1. Automate Your Savings
Set up automatic transfers from your checking account to your high-yield savings account immediately after you get paid. Even small, consistent contributions add up significantly over time, especially with a 5.25% APY. Automating takes the guesswork out of saving and ensures you prioritize your financial goals.
2. Clearly Define Your 2026 Goals
Knowing exactly what you’re saving for and by when provides powerful motivation. Whether it’s a down payment, a car, or a specific investment, quantify your goal and work backward to determine how much you need to save each month. This clarity makes your high-yield savings account a tool for a specific purpose.
3. Resist the Urge to Withdraw
Remember that the purpose of this account is to grow your savings for specific future goals. Avoid unnecessary withdrawals, as each withdrawal reduces the principal on which interest is compounded, slowing down your progress. Treat your high-yield savings account as a sacred space for your future.
4. Monitor Market Rates
While 5.25% APY is excellent, the market is dynamic. Keep an eye on the overall interest rate environment. If rates significantly increase and other banks begin offering much higher APYs, don’t hesitate to consider switching accounts. Portability is a key advantage of online high-yield savings accounts.
5. Leverage Sub-Accounts (If Available)
Some banks allow you to create multiple sub-accounts within your main high-yield savings account. This can be incredibly useful for managing different 2026 goals. For example, you could have one sub-account for a home down payment, another for a vacation, and a third for an emergency fund. This organizational method helps you track progress for each goal individually.
The Role of High-Yield Savings Accounts in Your Broader Financial Strategy
While a high-yield savings account with a 5.25% APY is a fantastic tool, it’s essential to understand its place within your overall financial strategy. It’s typically best suited for:
- Emergency Funds: Your emergency fund should be liquid and easily accessible, yet still earning interest. HYSAs are perfect for this.
- Short-to-Medium Term Goals (1-5 years): For goals like a car purchase, a home down payment (within a few years), or a large planned expense, an HYSA offers growth without the market volatility of investments.
- Holding funds before investment: If you’ve sold an asset or received a large sum and are waiting for the right investment opportunity, an HYSA can keep your money productive in the interim.
For long-term goals (5+ years), such as retirement, investments like stocks and bonds typically offer higher growth potential, albeit with higher risk. An HYSA complements these investments by providing a stable, low-risk component to your portfolio.
Understanding the Future of APY Rates
It’s important to have realistic expectations about interest rates. The current environment that allows for 5.25% APY on high-yield savings accounts is largely influenced by the Federal Reserve’s monetary policy. When the Fed raises its benchmark interest rate, banks tend to follow suit by increasing their savings rates to attract deposits. Conversely, if the Fed begins to cut rates, high-yield savings account APYs will likely decrease.
This doesn’t diminish the value of a high-yield savings account; it simply means that the specific 5.25% rate might fluctuate. The key is to always seek out the most competitive rate available at any given time and be prepared to move your money if a significantly better offer arises from another FDIC-insured institution. The competitive nature of online banking means that banks are constantly vying for deposits, often leading to attractive offers for consumers.
Common Misconceptions About High-Yield Savings Accounts
Let’s address a few common misunderstandings that might prevent people from utilizing HYSAs:
- "They’re too good to be true." High-yield savings accounts are legitimate financial products offered by FDIC-insured banks. Their higher rates are a result of lower operating costs and a competitive online market, not a scam.
- "My money isn’t safe." As long as the bank is FDIC-insured, your deposits are protected up to $250,000, just like at a traditional bank.
- "It’s too much hassle to switch banks." While it requires some initial setup, the process of opening an online HYSA and linking accounts is typically straightforward and can be completed in minutes online. The long-term benefits of higher earnings far outweigh the minor initial effort.
- "I’ll pay too much in taxes." The interest earned on high-yield savings accounts is taxable income. However, the amount is usually modest unless you have a very large sum saved. The tax implications are generally minor compared to the benefits of increased earnings. Always consult a tax professional for personalized advice.
Conclusion: Powering Your 2026 Goals with High-Yield Savings Accounts
For anyone serious about achieving their financial goals by 2026, a high-yield savings account offering a 5.25% APY (or a similarly competitive rate) is an indispensable tool. By understanding the features, comparing top contenders, and implementing smart savings strategies, you can significantly accelerate your wealth-building journey.
The digital age has democratized access to better financial products, and high-yield savings accounts are a prime example. Don’t let your money sit stagnant in a low-interest account. Take the proactive step today to research, compare, and open a high-yield savings account that will help you confidently stride towards your financial aspirations for 2026 and beyond.
Remember, consistent saving, combined with the power of compounding interest from a high-yield account, is a formula for financial success. Start your journey to smarter savings today!