Mastering Debt Repayment: Strategies to Save 15% on Interest by 2027
Debt can feel like a heavy burden, a relentless current pulling you further away from your financial goals. But what if you could not only navigate this current but also strategically steer your way to calmer waters, saving a significant amount of money in the process? This comprehensive guide will equip you with powerful debt repayment strategies designed to help you save a remarkable 15% on interest by 2027. This isn’t just about paying off debt; it’s about optimizing your financial future, reclaiming control, and building a solid foundation for lasting prosperity.
The journey to financial freedom often begins with a clear understanding of your current debt landscape. Many individuals feel overwhelmed by the sheer volume and complexity of their debts, leading to inaction or inefficient repayment methods. Our goal is to demystify this process, providing actionable steps and proven strategies that are both effective and sustainable. By focusing on smart repayment, you can dramatically reduce the total cost of your debt, freeing up valuable resources for savings, investments, or simply enjoying life without the constant pressure of high interest payments.
Saving 15% on interest by 2027 might seem like an ambitious target, but with the right approach and consistent effort, it is entirely achievable. This article will break down various debt repayment strategies, from popular methods like the debt snowball and avalanche to more advanced techniques such as debt consolidation and balance transfers. We’ll also delve into crucial aspects like budgeting, negotiating with creditors, and building an emergency fund, all of which play a pivotal role in accelerating your debt-free journey. Prepare to transform your financial outlook and embark on a path towards significant interest savings and ultimate financial liberation.
Understanding Your Debt Landscape: The First Step to Savings
Before you can effectively implement any debt repayment strategies, you need a crystal-clear picture of your current financial situation. This involves more than just knowing how much you owe; it requires a deep dive into the types of debt, interest rates, minimum payments, and repayment terms. Think of it as mapping out the terrain before embarking on a journey. Without a precise map, you might wander aimlessly, making less progress than you could.
Categorize Your Debts
Start by listing all your debts. This includes credit card debt, personal loans, student loans, car loans, mortgages, and any other outstanding balances. For each debt, record the following:
- Creditor Name: Who do you owe money to?
- Current Balance: How much do you still owe?
- Interest Rate (APR): This is crucial. Higher interest rates mean more money paid over time.
- Minimum Monthly Payment: What is the lowest amount you can pay each month to avoid penalties?
- Due Date: When is the payment due?
- Type of Debt: Is it secured (like a mortgage or car loan) or unsecured (like credit cards or personal loans)?
Organizing this information, perhaps in a spreadsheet, will give you an invaluable overview. You’ll quickly identify which debts are costing you the most in interest and which ones might be easier to tackle first.
Calculate Your Total Interest Paid
Many people are shocked when they calculate the total interest they’ve paid or are projected to pay over the life of their loans. Use online calculators or consult your loan statements to get a realistic estimate. Understanding this number is a powerful motivator for implementing effective debt repayment strategies. For example, if you have a credit card with a $5,000 balance and a 20% APR, and you only make minimum payments, you could end up paying thousands of dollars in interest alone over many years. Our goal is to reduce this figure by 15% by 2027, which translates to substantial real-world savings.
Assess Your Income and Expenses
A realistic budget is the backbone of any successful debt repayment plan. You need to know exactly how much money is coming in and where it’s going. Track every dollar for at least a month. Categorize your expenses into fixed (rent, loan payments) and variable (groceries, entertainment). Identify areas where you can cut back, even slightly, to free up more money for debt repayment. Every extra dollar you put towards your principal balance can save you exponentially more in interest over time.
Popular Debt Repayment Strategies: Snowball vs. Avalanche
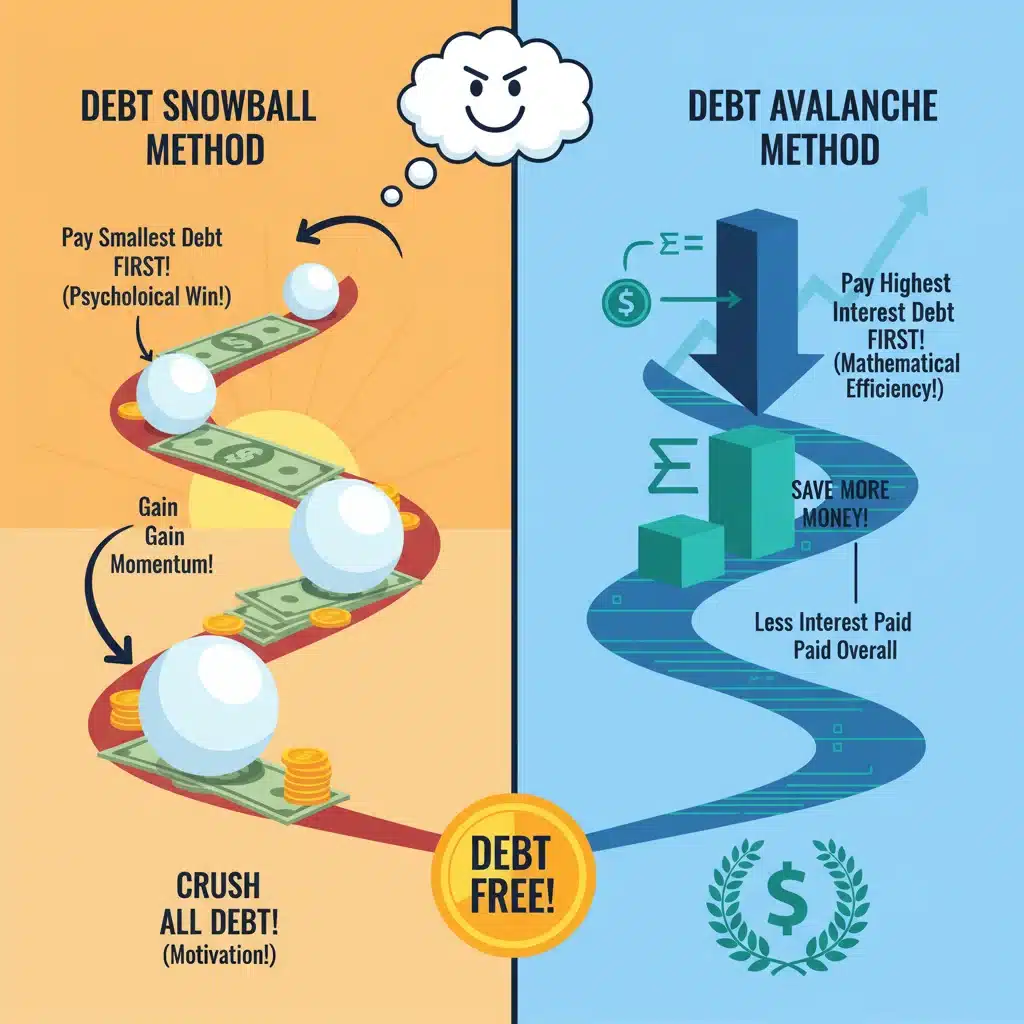
Once you have a clear picture of your debts, it’s time to choose a repayment strategy. Two of the most popular and effective methods are the debt snowball and the debt avalanche. Both aim to accelerate your debt repayment, but they approach the problem from different angles.
The Debt Snowball Method
The debt snowball method focuses on psychological wins to keep you motivated. Here’s how it works:
- List all your debts from the smallest balance to the largest, regardless of the interest rate.
- Make minimum payments on all debts except the smallest one.
- Throw all extra money you can find at the smallest debt until it’s paid off.
- Once the smallest debt is gone, take the money you were paying on that debt (minimum payment + extra payments) and apply it to the next smallest debt.
- Continue this process, “snowballing” your payments, until all debts are paid off.
The advantage of the debt snowball is the quick wins. Paying off a small debt provides a boost of motivation, making you feel like you’re making progress, which can be crucial for staying committed to your debt repayment strategies. While mathematically it might cost you slightly more in interest than the avalanche method, the psychological benefits often outweigh this difference for many individuals.
The Debt Avalanche Method
The debt avalanche method is the mathematically optimal choice for saving the most money on interest. Here’s how it works:
- List all your debts from the highest interest rate to the lowest, regardless of the balance.
- Make minimum payments on all debts except the one with the highest interest rate.
- Direct all extra money you can find towards the debt with the highest interest rate until it’s paid off.
- Once the highest interest debt is gone, take the money you were paying on that debt (minimum payment + extra payments) and apply it to the debt with the next highest interest rate.
- Continue this process until all debts are paid off.
The debt avalanche method ensures you tackle the most expensive debts first, significantly reducing the total amount of interest you pay over time. If your primary goal is to save the maximum amount of money, this is the superior strategy. Both methods are powerful debt repayment strategies; choose the one that aligns best with your personality and financial discipline.
Advanced Debt Repayment Strategies for Maximizing Savings
Beyond the snowball and avalanche, several other powerful debt repayment strategies can help you save even more on interest, especially when dealing with high-interest debts like credit cards.
Debt Consolidation
Debt consolidation involves combining multiple debts into a single, new loan, often with a lower interest rate and a single monthly payment. This can simplify your finances and potentially save you a significant amount on interest. Common consolidation options include:
- Personal Loans: Unsecured loans that can be used to pay off credit card debt or other high-interest loans. They typically have fixed interest rates and repayment terms.
- Balance Transfer Credit Cards: These cards offer an introductory 0% APR for a promotional period (e.g., 12-18 months) on transferred balances. This can be a fantastic way to pay down high-interest credit card debt without incurring additional interest for a limited time. Be mindful of balance transfer fees and ensure you can pay off the balance before the promotional period ends, or the interest rate will revert to a much higher rate.
- Home Equity Loans/Lines of Credit (HELOCs): If you own a home, you might be able to borrow against your home equity. These often have lower interest rates than unsecured loans, but they use your home as collateral, meaning you risk foreclosure if you can’t make payments.
Carefully evaluate the terms and conditions of any consolidation option. A lower monthly payment might sometimes come with a longer repayment period, potentially leading to more interest paid overall if the interest rate isn’t significantly lower. Always do the math to ensure it aligns with your goal of saving 15% on interest by 2027.
Negotiating with Creditors
Many people don’t realize that their creditors might be willing to negotiate, especially if you’re experiencing financial hardship. If you’re struggling to make payments, reaching out to your creditors can lead to several beneficial outcomes:
- Lower Interest Rates: Some creditors might agree to lower your interest rate, even temporarily, to help you get back on track.
- Reduced Minimum Payments: They might adjust your minimum payment to a more manageable amount.
- Payment Plans: They could offer a structured payment plan that fits your budget.
- Debt Settlement: In more extreme cases, if you’re severely delinquent, a creditor might agree to settle your debt for less than the full amount owed. This can have a negative impact on your credit score, so it should be considered a last resort.
Don’t be afraid to make that call. A proactive approach can prevent further financial distress and open doors to more manageable debt repayment strategies.
Essential Supporting Habits for Debt Repayment Success
While specific debt repayment strategies are crucial, their effectiveness is amplified by adopting certain financial habits. These habits form the bedrock of sustainable financial health and will significantly contribute to your goal of saving 15% on interest by 2027.
Create and Stick to a Detailed Budget
We touched upon this earlier, but it bears repeating: a budget is your financial roadmap. It helps you understand where your money is going and identify areas where you can cut back to free up more funds for debt repayment. Use budgeting apps, spreadsheets, or even pen and paper. The key is consistency. Regularly review and adjust your budget to reflect changes in income or expenses. Every dollar saved on discretionary spending can be channeled directly towards reducing your principal balance, thereby reducing the total interest paid.
Build an Emergency Fund
One of the biggest threats to a debt repayment plan is an unexpected expense. A car repair, medical bill, or job loss can derail your progress and force you back into debt. An emergency fund acts as a financial safety net, protecting your debt repayment efforts. Start small, even if it’s just $500 or $1,000, and gradually build it up to cover 3-6 months of essential living expenses. Having this buffer prevents you from relying on high-interest credit cards when unforeseen events occur, directly supporting your goal of saving on interest.
Increase Your Income
While cutting expenses is important, sometimes there’s a limit to how much you can trim. Increasing your income provides more fuel for your debt repayment engine. Consider:
- Side Gigs: Freelancing, ride-sharing, tutoring, or selling items online.
- Overtime: If available at your current job.
- Asking for a Raise: If you’ve been a valuable employee, negotiate for better compensation.
- Selling Unused Items: Declutter your home and earn some extra cash.
Every extra dollar earned and applied to your debt accelerates the process and reduces the total interest you’ll pay.
Avoid New Debt
This might seem obvious, but it’s a critical component of successful debt repayment strategies. While you’re aggressively paying down existing debt, resist the temptation to take on new debt. This means putting away credit cards, avoiding unnecessary purchases, and living within your means. If you’re using a balance transfer card, be extremely disciplined about not charging new purchases to it.
Monitoring Progress and Staying Motivated
The journey to becoming debt-free and saving a significant amount of interest is a marathon, not a sprint. Regular monitoring and strategies for staying motivated are essential to reach your goal of saving 15% on interest by 2027.
Track Your Progress Regularly
Seeing your debt balances decrease is incredibly motivating. Use a spreadsheet, a debt tracking app, or even a simple visual chart to track your progress. Update it monthly after you make your payments. Celebrate small milestones, like paying off a credit card or reaching a certain percentage of your total debt paid. This tangible evidence of your hard work reinforces positive behavior and keeps you focused on your long-term objective.
Adjust Your Strategy as Needed
Life happens, and your financial situation might change. Be flexible and willing to adjust your debt repayment strategies. If you get a raise, allocate a larger portion to debt. If an unexpected expense arises, temporarily pause extra payments and focus on minimums until your emergency fund is replenished. The best plan is one that can adapt to your circumstances.
Educate Yourself Continuously
The world of personal finance is always evolving. Stay informed about new financial products, interest rates, and economic trends. Read books, listen to podcasts, and follow reputable financial blogs. The more knowledgeable you are, the better equipped you’ll be to make smart financial decisions and optimize your debt repayment strategies.
Seek Professional Help if Necessary
If you feel overwhelmed or are struggling to make progress, don’t hesitate to seek professional help. Non-profit credit counseling agencies can provide personalized advice, help you create a debt management plan, and even negotiate with creditors on your behalf. For more complex situations, a financial advisor can offer comprehensive planning. There’s no shame in asking for guidance; it’s a smart move towards financial well-being.
The Path to Saving 15% on Interest by 2027: A Roadmap
Let’s put it all together into a tangible roadmap for achieving your goal of saving 15% on interest by 2027. This isn’t just about applying one strategy; it’s about integrating multiple approaches and maintaining discipline.
Year 1: Foundation and Aggressive Attack (2024)
- Month 1-2: Debt Assessment & Budget Creation. Complete your debt inventory. Create a detailed budget, identifying at least 10% of your income that can be redirected to debt above minimum payments.
- Month 3-6: Strategy Selection & Initial Implementation. Choose between debt snowball (if motivation is key) or debt avalanche (if mathematical savings are paramount). If credit card debt is high, explore balance transfer cards with 0% APR. Transfer balances and commit to paying them off within the promotional period.
- Month 7-12: Emergency Fund & Income Boost. Start building a mini-emergency fund ($1,000). Seek opportunities to increase income (side hustle, overtime) and direct 100% of this new income towards your chosen debt repayment strategy.
- Interest Savings Target: Aim for an initial 3-5% reduction in your total projected interest payments for debts tackled.
Year 2: Optimization and Consolidation (2025)
- Month 1-6: Re-evaluate & Consolidate. Review your progress. If you’ve paid off some smaller debts, re-allocate those funds. If high-interest personal loans remain, explore debt consolidation loans with lower fixed rates.
- Month 7-12: Negotiate & Automate. Contact creditors of remaining high-interest debts to inquire about lower rates. Automate your debt payments to avoid late fees and ensure consistency. Increase your emergency fund to 1-2 months of expenses.
- Interest Savings Target: Aim for an additional 5-7% reduction, bringing your total projected interest savings to 8-12%.
Year 3: Accelerate and Sustain (2026)
- Month 1-6: Aggressive Repayment. With fewer debts and potentially lower interest rates, you should have more disposable income. Aggressively apply this towards your remaining principal balances. Focus on the largest remaining high-interest debts.
- Month 7-12: Financial Review & Future Planning. Conduct a thorough financial review. Assess your progress towards the 15% interest saving goal. Begin planning for post-debt financial goals, such as maximizing retirement savings or investing. Fully fund your emergency fund (3-6 months of expenses).
- Interest Savings Target: Aim to achieve or exceed the 15% interest savings goal by the end of 2026, well ahead of the 2027 deadline.
Year 4: Debt-Free Living & Wealth Building (2027 and Beyond)
- Maintain Discipline: Continue to live within your means and avoid new unnecessary debt.
- Redirect Funds: The money you were once dedicating to debt repayment can now be redirected towards wealth accumulation – investments, retirement accounts, saving for a down payment, or fulfilling other financial aspirations.
- Enjoy Financial Freedom: Reaching this stage means significantly less financial stress and more control over your life.
Conclusion: Your Journey to Financial Empowerment
Embarking on a journey to optimize your debt repayment is one of the most empowering financial decisions you can make. By diligently applying these debt repayment strategies, from understanding your debt landscape to implementing the snowball or avalanche method, exploring consolidation, and fostering healthy financial habits, you are not just paying off loans; you are systematically dismantling a barrier to your financial freedom.
The target of saving 15% on interest by 2027 is a powerful motivator, a tangible goal that can guide your actions and fuel your determination. Remember, every extra dollar you pay towards principal, every percentage point you reduce your interest rate, and every smart financial decision you make contributes to this overarching objective. It requires discipline, consistency, and a willingness to adapt, but the rewards—tens of thousands of dollars saved and the peace of mind that comes with financial control—are immeasurable.
Start today. Take that first step to categorize your debts, create your budget, and choose the strategy that resonates most with you. Your future self, free from the burden of high-interest debt and empowered by significant savings, will thank you. The path to financial wellness is within your grasp; seize it with these proven debt repayment strategies.